
Published:
Newsquawk Desk
US Market Open: Talks between Iran and Gulf states postponed and Saudi shuts a key oil pipeline; crude benchmarks gain
0:00--:--
- Iranian Foreign Ministry Spokesperson said that Saudi Arabia insisted that the meeting between Iran and Gulf nations in Oman not to take place and it will be postponed to another date due to the Yemen situation.
- US President Trump said he warned Ukraine to stop targeting Russian oil refineries, as strikes have shut down diesel refining and helped lift prices of the fuel to record levels.
- Anthropic CEO Amodei urged a slowdown in the development of the most advanced AI systems to prevent AI from slipping beyond human control.
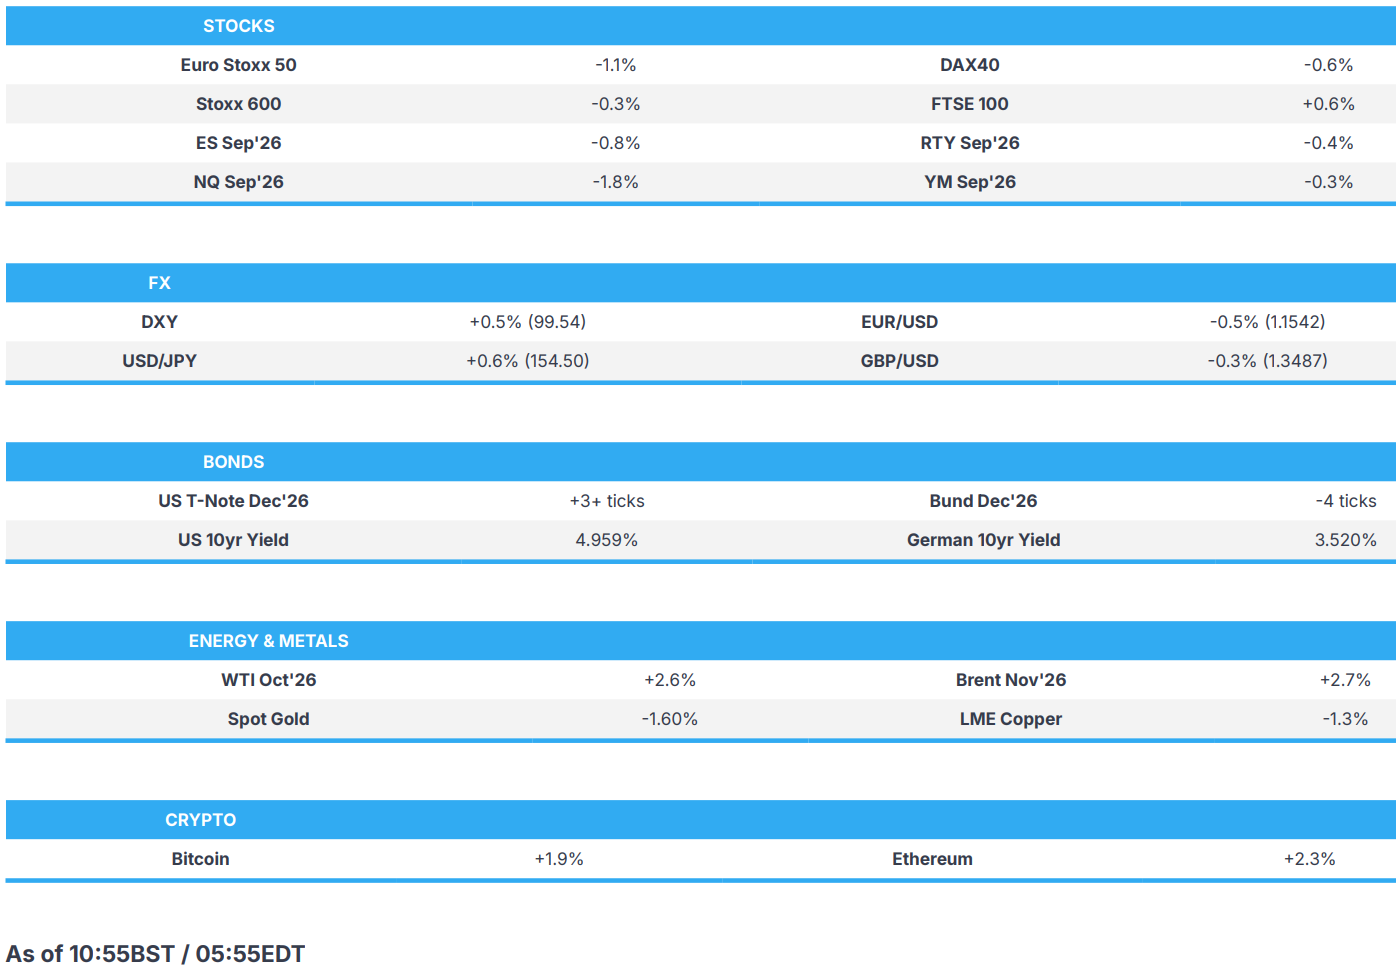
- US equity futures fall, Semis hit the hardest on worries of less capex investment.
- DXY firms on Fed rate hike bets and higher energy prices; JPY underperforms.
- Fixed income benchmarks mixed despite higher energy prices (Brent +2.7%).
- Looking ahead, highlights include the Canadian CPI (Aug). Speakers include ECB's Cipollone & Lagarde.
SNAPSHOT
EUROPEAN TRADE
EQUITIES
- European bourses are broadly lower to start the week, with Italy's FTSE MIB the underperformer, while the SMI and FTSE 100 print decent gains, helped by updates in the Pharma space. Sectors point to a mixed picture. Health Care tops the sector pile, with Optimised Personal Care and Food, Beverages & Tobacco rounding out the leaders. Tech leads the downside, followed by Basic Resources and Industrials.
- The overnight downside was driven by Anthropic CEO Amodei, urging a slowdown in the development of the most advanced AI systems to prevent AI from slipping beyond human control. The effect this has on semiconductors may be slower capex investment; however, Amodei insists that pacing AI capabilities will not necessarily translate into reduced spending or growth. As a result, SK Hynix and Samsung Electronics slumped overnight (-6.4% and -4.1%, respectively), while ASML is currently down by 5.2%, while US behemoth NVIDIA slides by 2.5% pre-market.
- US equity futures are lower across the board, with the NQ the laggard given the AI woes detailed above. Focus this week will be on the FOMC rate decision, with markets pricing in an 89% chance of a hike.
- Click for the sessions European pre-market equity newsflow
- Click for the additional news
FX
- Snapshot: G10s are lower against the broadly stronger USD, as traders increase their bets on a rate hike this week. JPY is the clear underperformer this morning on widening yield differentials, followed closely by the Kiwi. The Loonie fares a touch better vs peers, thanks to higher energy prices and simmering down in US-Canada tensions; Trump recently downplayed leaving the USMCA, with both countries suggesting that a deal would be found “fairly soon”.
- DXY is stronger this morning and currently trades towards the upper end of a 99.07 to 99.60 range. Much of the upside comes as a number of sell-side banks bring forward their bets of a hike this week; Goldman Sachs the latest to do so. As it stands, money markets assign an 86% chance of a hike this week. There’s not a whole lot on the docket heading into the Wednesday meeting, so the index will likely remain within familiar ranges – though any updates on the geopolitical situation would spur a break in either direction.
- JPY is the clear underperformer this morning on higher expectations that the Fed will join the BoJ in hiking rates this week. Much of the strength in the JPY over the past couple of weeks has been attributed to narrowing yield differentials (hawkish BoJ), and joint intervention worries. Another bout of near-term strength in the JPY would likely require a hawkish BoJ on Friday, and particularly, board members explicitly guiding for a faster pace of rate hikes. Recent source reports have suggested that the Bank could do this. USD/JPY currently holds within a 153.37 to 154.61 range.
FIXED INCOME
- Global fixed benchmarks are mixed. USTs (+3+ ticks) hold afloat, whilst Bunds (-4 ticks) and Gilts (-3 ticks) have been pressured by another bout of strength in the energy complex. For reference, energy benchmarks are moving higher on a) postponement of Iran-Gulf talks on the Strait and b) Saudi shutting a key pipeline.
- USTs remain firmer this morning, and currently hold within a 106-03 to 106-10+ range. Strength which comes despite sell-side banks boosting their bets of a hike this week, and higher energy prices. The environment is clouded by fiscal and geopolitical uncertainty. This is made evident by sustained elevated yields; the US 10-year (4.96%) trades just shy of the 5.00% mark, and a hawkish Fed mid-week will likely see it top that mark.
- Bunds and Gilts have been pressured throughout the European morning as energy benchmarks gradually picked up. Gilts are pressured given their high dependency on external energy, and as traders eye the BoE this week.
- BTPs have steadily fallen throughout the morning and are currently at the lower end of their 111.96-112.57 range. After-hours on Friday, Fitch affirmed Italy at 'BBB+'; outlook stable. The credit agency commented that the "continued increase in public debt/GDP over the medium term" is a risk that could result in a downgrade. Regarding the upcoming elections, Fitch observed that the "recent political stability has been a positive anchor for Italy's sovereign rating", and that the law to switch the proportional electoral system could favour a stable government.
COMMODITIES
- Snapshot: Crude benchmarks are stronger this morning on a) the postponement of the Iran-Gulf nations meeting, and b) Saudi Arabia shutting the East-West pipeline. Spot gold is hampered by a stronger USD, whilst base metals have been dented by the risk-tone.
- To recap the geopolitical environment briefly, Oman postponed the Persian Gulf meeting on Monday, where Iran had planned to formally unveil a temporary shipping lane agreement for the Strait of Hormuz. Axios suggested that Saudi was concerned that the new Strait proposal would effectively establish a new status quo; however, the Iranian FM Spokesperson suggested that the meeting was postponed due to the Yemen-Saudi situation. On the supply front, Saudi shut the East-West pipeline, which reportedly threatens the loss of c. 4% of global supply. Marhelm sources pointed out that repairs could take over a month.
- Given the above, crude benchmarks gapped higher at the open and traded sideways for most of the APAC session. As the European session got underway, the oil complex caught another bid higher (on reports that the IRGC shot down a US drone, and following Iran FM comments). As it stands, Brent Nov’26 (+2.6%) holds at the top end of a USD 106.11/bbl to 108.65/bbl range; WTI Nov’26 (+2.6%) also holds at the upper end of a USD 101.59/bbl to 103.83/bbl range.
- Spot gold (-1.6%) has been hampered by a stronger USD (increased rate hike bets) and higher energy prices. As such, the yellow metal currently sits at the bottom end of a USD 4,279.28/oz to USD 4,355.40/oz range. This week, action for gold will be dictated by any geopolitical developments and the Fed mid-week. Elsewhere, base metals are entirely in the red, given the downbeat risk tone. 3M LME Copper currently trades at the lower end of a USD 14,100-14,236/t range.
- Saudi oil buyers and traders warned the kingdom could run out of oil stocks for exports if it doesn’t restart a major pipeline to the Red Sea within days, which could lead to a loss of up to 4% of global supply.
- Marhelm cited sources within Saudi Arabia that stated the damages to the East-West Pipeline will take over a month to repair due to a lack of spare parts and deeply impacted supply chains. Furthermore, it was stated that minor damages to the pipe have been repaired, but catastrophic damage to pumping infrastructure will take longer to fix.
- Exxon (XOM) executive said that they see US LNG supply growing to make c. 30% of global LNG supply by 2030.
- Shell (SHEL LN) executive said around 36mln tonnes of LNG from the Middle East have been lost to date.
TRADE/TARIFFS
- US President Trump said he’s not worried about Chinese President Xi calling off their summit scheduled for this month, while Japanese media reported that Beijing informed Washington it will cancel the planned summit if any new arms sales to Taipei are approved.
- US President Trump suggested he may be willing to permit a Chinese car company to build EVs in the US if it did so with US workers. It was separately reported that President Trump said the US will lift tariffs on Irish whiskey.
- US President Trump expressed optimism regarding resolving the trade dispute with Canada soon and downplayed prospects of leaving the USMCA, while Trump took verbal jabs at Europe regarding trade and immigration during his Ireland visit.
- Canadian PM Carney is set to meet with UK PM Burnham as Canada deepens its relations with Europe, while Carney proposed that Canada should become the EU's first 'associate member', and the bloc is said to be open to the idea.
NOTABLE EUROPEAN HEADLINES
- Exit polls showed that Sweden's centre-left opposition is on course for an election win in a blow to the far-right, while broadcaster SVT's revised projections suggest the opposition bloc is on course to win 175 seats and the incumbent right-wing bloc is on course to win 174 seats.
- Swedish election is reportedly too close to call as total count may take days.
- Fitch affirmed Italy at 'BBB+'; outlook stable.
NOTABLE EUROPEAN DATA RECAP
- Swedish CPIF Final (Aug YY) 0.7% vs. Exp. 0.7% (Prev. 0.7%).
- Swedish CPIF Final (Aug MM) -0.3% vs. Exp. -0.3% (Prev. -0.3%).
CENTRAL BANKS
- ECB President Lagarde said the current inflation shock is longer-lasting, with the volatility and pressure on energy prices to continue amid the conflict in the Middle East.
- ECB's Kazaks said the case is building for more tightening and the ECB can afford to act stepwise without rushing.
- ECB's Simkus said he cannot exclude action at any meeting, adding that December is a natural time to assess the situation more.
- ECB’s Kazimir said all options will be considered for the next decision, but action will be taken if necessary.
NOTABLE US HEADLINES
- US House Speaker Johnson said US President Trump's proposed USD 5,000 dividend for every US adult would require congressional approval, contradicting Trump's claim that the payments can be made without authorisation.
GEOPOLITICS
MIDDLE EAST
- US President Trump said Iran-backed Houthis asked the US not to target them, while Trump reiterated that he expects the Iran war to end this year, possibly after the Midterms, but also suggested that the US could stay in Iran and keep the oil, like the Venezuela deal.
- Iran's Foreign Ministry Spokesperson said that Saudi Arabia insisted that the meeting between Iran and Gulf nations in Oman not to take place and it will be postponed to another date due to the Yemen situation. The spokesperson added that the MoU between Iran and Oman is the result of weeks of intensive negotiations and was drafted with full respect for the sovereign rights of the two countries. On the situation in Iran, Baghaei said Iran has no interference in Yemen and denied any participation in the attacks on a Saudi oil pipeline. On the reports about nuclear activity in Pickaxe mountain, he called them "baseless".
- Oman postponed the Persian Gulf Foreign Ministers meeting for an indefinite period. This was later confirmed by Iran.
- Oman's Energy Minister said the Strait of Hormuz will be open and it's probably a short-term situation, while he is pleased Oman is still able to continue producing oil and gas. Furthermore, he stated that skyrocketing oil and LNG prices are not sustainable and the situation should stabilise in the medium-term.
- Iran's Akbari said "The Iranian route can be a sustainable alternative to the Red Sea route and ensure the connection of Asia, India, China and Singapore to Europe in times of crisis"
- Iran’s PGSA published an updated list of 77 vessels allegedly violating Iranian Strait of Hormuz protocols. The listed vessels could face future passage restrictions, including fines, detention or confiscation. Vessels cooperating with sanctioned ships will also be added to the list.
- Houthi Spokesperson claimed the attack on Saudi's King Khaliq Air base, stating "The Armed Forces will continue to carry out significant military operations towards Saudi territory as long as it continues its unjust aggression against our people".
- Saudi Crown Prince met the US CENTCOM chief to discuss the latest regional developments, according to Saudi state TV.
- Saudi civil defence issued emergency alerts for Khamis Mushait, Abha City, Jizan region and Najra province but said the danger has passed.
- Saudi Yanbu oil exports were halted after a pipeline attack, while weekend reports noted multiple explosions struck Saudi Arabia’s Yanbu Industrial City on Sunday.
RUSSIA-UKRAINE
- US President Trump said he warned Ukrainian President Zelensky to stop targeting Russian oil refineries as strikes have shut down diesel refining and helped lift prices of the fuel to record levels.
OTHER
- US President Trump said he could settle the UK-Argentina dispute regarding the Falklands, while he separately commented that he would love to see Ireland unified.
- North Korea fired multiple short-range ballistic missiles towards its east coast on Saturday.
CRYPTO
- Bitcoin surged at the start of Asian trade and currently resides just shy of its USD 78.24k peak despite the risk-off tone.
APAC TRADE
- APAC stocks were ultimately mixed after gradually improving from the initial risk-off mood seen at the start of the session, which had been triggered by AI-related selling after key industry executives called for a slowdown in AI development. There were also headwinds from the conflict in the Middle East after Saudi Arabia shut its East-West Pipeline following drone attacks last week, which threatens the loss of 4% of global supply, while Oman postponed the Persian Gulf meeting on Monday, where Iran had planned to formally unveil a temporary shipping lane agreement for the Strait of Hormuz.
- ASX 200 was kept afloat in range-bound trade amid resilience in defensives and the consumer sectors, while there were some comments from RBA Assistant Governor Hunter, who stated that Australian household spending is holding up okay and business investment is showing signs of strength, but also noted inflation remains above target.
- Nikkei 225 slumped at the open amid notable losses in Kioxia and with SoftBank dropping by double-digit percentages owing to its heavy AI exposure, although the index is well off today's worst levels amid mixed yields in Japan and with the TOPIX index in the green.
- KOSPI underperformed amid losses in semiconductor heavyweights, while today marks the start of the Korea Exchange extending trading hours to allow stock trading until 8pm local time.
- Hang Seng and Shanghai Comp pared opening losses and moved into the green, but with upside capped ahead of tomorrow's activity data, while US President Trump said he is not worried about Chinese President Xi cancelling their planned summit after reports that Beijing informed Washington it will cancel the planned summit if any new arms sales to Taipei are approved.
NOTABLE ASIA-PAC HEADLINES
- PBoC plans to expand the yuan offshore market and will consider expanding the central bank's macroprudential and financial stability roles, adding that they will innovate macroprudential policy tools and support steady economic recovery and growth.
NOTABLE APAC DATA RECAP
- Chinese Outstanding Loan Growth (Aug YY) 4.9% vs. Exp. 5.1% (Prev. 5.1%).
- Chinese M2 Money Supply (Aug YY) 7.5% vs. Exp. 7.6% (Prev. 7.7%).
- Chinese Total Social Financing (Aug) 1660.0B vs. Exp. 2040B (Prev. 1410.0B).
- Chinese New Yuan Loans (Aug) 60.0B vs. Exp. 400B (Prev. -340.0B).
- Japanese Industrial Production Final (Jul YY) 3.9% (Prev. 4.9%).
- Japanese Industrial Production Final (Jul MM) -0.2% vs. Exp. 0.1% (Prev. 1.9%).
The full platform
Have a play with the Newsquawk platform.
Build a watchlist, pop the widgets out, experiment with the filters and sample the squawks. The whole workspace is open to try — no signup, no card. Newsquawk Pro adds the live feed for £24.99 for 7 days.
Free. No signup, no card.
Both market opens, in your inbox.