
Published:
Newsquawk Desk
US Market Open: Risk on action with crude benchmarks lower amidst hope of a Hormuz deal
0:00--:--
- Iranian Foreign Minister Araghchi said Iran presented a proposal to the US through mediators this week to reopen the Strait of Hormuz and restart negotiations towards a final deal; Brent -1.6%.
- Chinese President Xi said China and the US reached a common understanding on many issues.
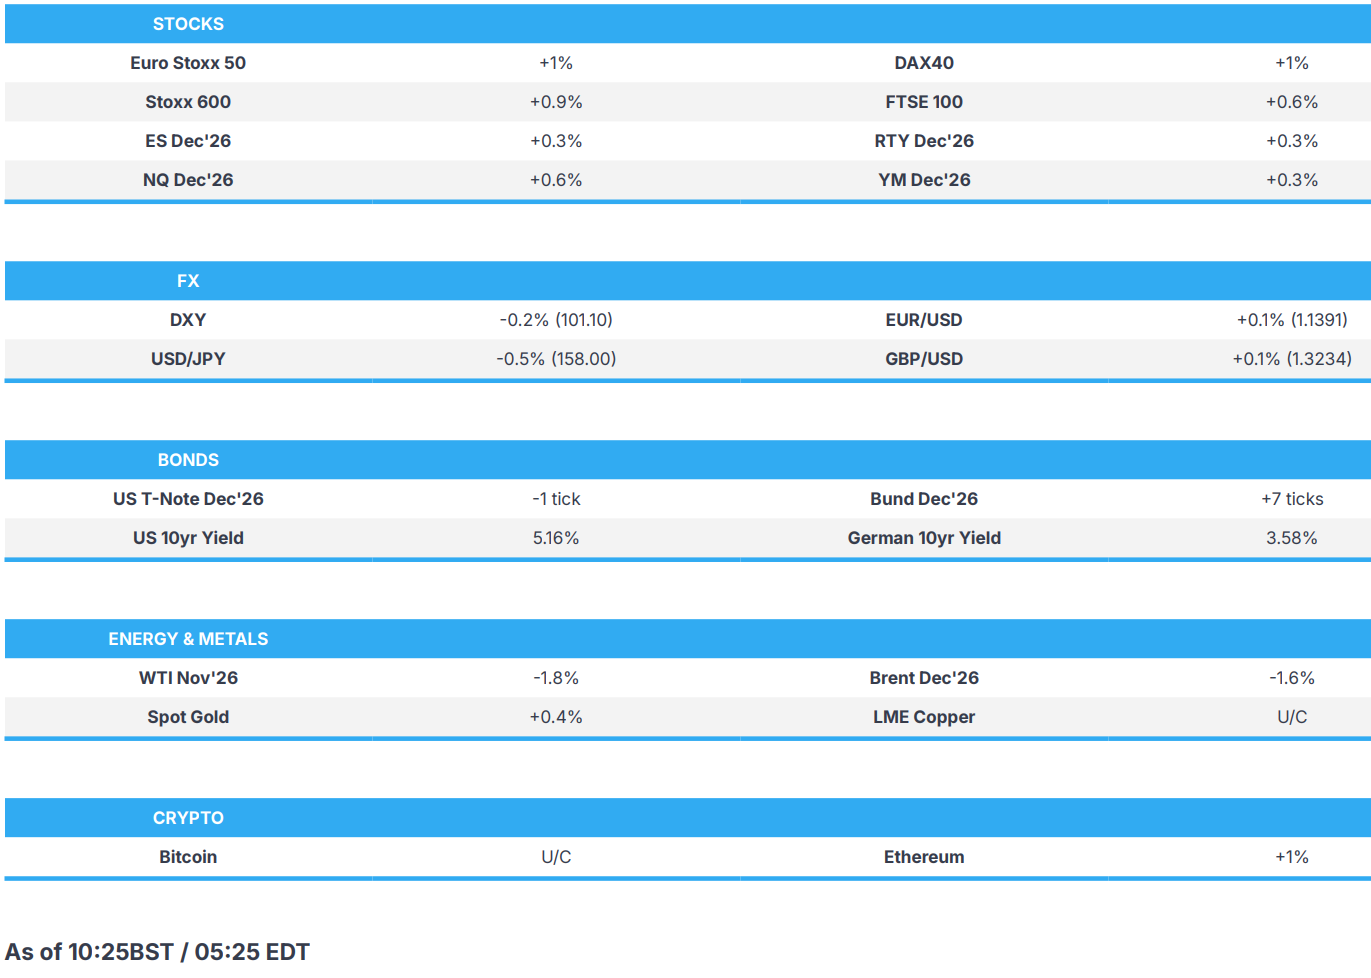
- European bourses gain as Iran offers hope of the reopening of the Strait of Hormuz; US equity futures follow suit, NQ +0.6%.
- DXY is slightly lower, whilst the JPY gains after Trump voiced concerns about a weak JPY to PM Takaichi.
- Looking ahead, highlights include US Durable Goods Orders (Aug), Atlanta Fed GDP (Q3). Speakers include Fed's Hammack & Schmid, ECB's Vujcic. Credit ratings, including Moody's on the EU & Italy, and Scope Ratings on the EU.
SNAPSHOT
LOOKING AHEAD
- Looking ahead, highlights include US Durable Goods Orders (Aug), Atlanta Fed GDP (Q3). Speakers include Fed's Hammack & Schmid, ECB's Vujcic. Credit ratings, including Moody's on the EU & Italy, and Scope Ratings on the EU.
- Click here for the Week Ahead preview
IRAN CONFLICT
Diplomacy:
- Iran Foreign Minister Araghchi said Iran presented a proposal to US through mediators this week to reopen the Strait of Hormuz and restart negotiations towards a final deal, while it called for US to meet certain conditions within 7 days, according to CNN.
- Iranian President Pezeshkian said in Fox News interview that Iran does not want a nuclear bomb. They reached an agreement with the US President that was signed, and are still ready to move forward based on the same principles, adds it wasn't Iran that closed the Strait of Hormuz and it was open. They didn't seek war and that it was imposed on them, while they don't seek war but will defend themselves. They didn't start the war but will respond decisively.
- Iranian President Pezeshkian said Iran is ready for an agreement with the US and makes demands only within the framework of international law and could give up highly enriched uranium if it reaches an agreement with the US, according to TASS.
- Iran's President Pezeshkian said Tehran wants to revive its ceasefire memorandum of understanding with the US before the November midterm elections, saying Iran does not want talks delayed until after the vote. said:. Iran is open to inspections of its nuclear facilities and denies that Tehran is seeking to assassinate President Trump or his family.
- Iran's Foreign Minister Araghchi said the Strait of Hormuz can reopen if certain conditions are met by the US and that it would be better to implement before the Midterms, according to a Sky reporter.
- Sources say a return to the June 18 memorandum of understanding between Iran and the US is no longer sought by either side, with both seeking amendments to some clauses, further complicating negotiations, Al-Akhbar reported.
- Pakistan's Defence Minister said intensive efforts are underway to establish a mechanism for ending the conflict as quickly as possible and reopening the Strait of Hormuz, according to Tasnim.
Please see the geopolitics section below for further details
EUROPEAN TRADE
EQUITIES
- European bourses (STOXX 600 +0.8%) are entirely in the green. The IBEX 35 (+1.2%) outperforms this morning, joined closely by the DAX 40 (+1%). The bullish bias seen this morning is facilitated by increased hopes of the reopening of the Strait of Hormuz. This comes after the Iranian President said that Iran presented a proposal to the US through mediators this week to reopen the Strait of Hormuz and restart negotiations towards a final deal. Whilst nothing is concrete at this stage, the path to diplomacy appears to be opening.
- European sectors hold a strong positive bias, with cyclical industries holding towards the top of the pile. Basic Resources tops the sectoral list, joined closely by Banks and Travel & Leisure. The latter benefits from lower oil prices and the general risk tone. Unsurprisingly, Energy resides at the foot of the pile. Food Beverage and Tobacco is the other sector in the red.
- Key movers: UBS (+3%, reportedly considering a merger with a foreign company as it looks to move out of Switzerland), Airbus (-1.8%, identified a corrosion protection defect affecting more than 500 A321neos), Leonardo (U/C, reportedly involved in the Airbus defect).
- US equity futures are entirely in the green this morning, following the positive mood seen across Europe. The tech-heavy NQ (+0.5%) outperforms the ES and RTY (+0.3%), with yields also easing off near-term highs. In the pre-market: Akamai (+21%, secures a USD 11.6bln deal with Anthropic), Costco (-0.3%, Q4 beat estimates but membership slowdown weighs).
FX
- DXY is modestly softer amid lower oil prices and after the Yen-led move weighed on the index (see below), although the Buck remains underpinned by this week's rise US yields and expectations for further Fed tightening, with DXY posting four consecutive sessions of gains this week thus far. DXY currently resides in a 101.11-101.30 at the time of writing,
- JPY is the clear G10 outperformer, with USD/JPY sliding ~30-40 pips on several separate occasions overnight and this morning, price action that can also be seen across other JPY crosses. The move comes after comments from Japanese Finance Minister Katayama, who stated that US President Trump voiced concerns about yen weakness, while she reiterated Japan will closely coordinate with the US on foreign exchange.
- EUR/USD is modestly firmer, with much of the upside stemming from the JPY-induced pressure on DXY rather than any fresh bloc-specific catalyst. The pair remains tucked within yesterday's 1.1359-1.1399 range, with today's parameter between 1.1368-1.1390.
- GBP/USD is modestly firmer but remains well below 1.3300 following this week's Sterling weakness. UK-specific catalysts are light, leaving broader USD dynamics to dictate price action. Cable currently resides in a 1.3209-1.3241 range.
- Antipodeans are modestly firmer intraday with fresh domestic catalysts are limited, with moves largely reflecting the broader easing in the Dollar, whilst mainland Chinese participants were away overnight. AUD/NZD is modestly firmer but off highs in a 1.2375-1.2409 range.
- Goldman Sachs lowers USD/JPY 3-month forecast to 158.00 from 162.00, 6-month forecast to 155.00 from 163.00 and 12-month forecast to 150.00 from 165.00.
FIXED INCOME
- A modestly bullish start to the final session of the week for fixed, led by downside in the energy space after the overnight Strait of Hormuz related commentary. Since then, updates have been relatively light and thus the rebound in benchmarks has been modest.
- As it stands, USTs are set to end the week with downside of nearly a full point, but some 10 ticks off the WTD 104-14+ low. In brief, the week was characterised by further yield upside given geopolitical and, pertinently, diesel updates. The 30yr hit a 5.50% peak, firmer by 20bps on the week at that point, while around 5bps off highs as it stands, the move remains significant and resilient.
- Further out, the general desk view is that the move has further to run given the US economic backdrop, continued Middle East uncertainty and associated supply disruption (and elevated shipping costs, added to by record low Rhine levels), potential US diesel measures, AI spend and a credibly hawkish Fed. Factors which are all indicative of further yield upside.
- Gilts are firmer by c. 30 ticks but just off best levels. Providing some relative respite to UK yields, but nonetheless the 10yr is 6bps firmer at 5.34% WTD and over 25bps MTD, despite the BoE holding the Bank Rate at 3.75% in September.
- Finally, EGBs follow suit to the above. Bunds are firmer by around 25 ticks, just off a 119.95 peak. Specifics for the space light. Focus remains on the above points, and also the wholesale changes set to impact the ECB over the next few months, as Schnabel leaves post-December, Lagarde potentially early-2027 and Lane in May 2027.
- Japan sold JPY 649bln in 10yr, 20yr and 30yr JGBs in enhanced liquidity auction; b/c 2.95 vs. Prev. 3.20. Highest accepted spread +0.032% vs. Prev. -0.011%. Allotment of bids at highest spread 80.1862% vs. Prev. 58.2741%.
- Australia sold AUD 1bln 2.5% May 2030 bonds; average yield 5.0368% and bid/cover 4.34×.
COMMODITIES
- WTI Nov and Brent Dec futures are softer on the session, with the complex pressured by growing diplomatic hopes around US-Iran negotiations and Hormuz. The US and Iran reportedly discussed a phased deal to reopen the Strait and end the US blockade, while Iranian Foreign Minister Araghchi said Tehran submitted a proposal through mediators to reopen Hormuz and restart negotiations towards a final deal. However, Al-Akhbar subsequently reported that neither side is seeking a return to the June 18 MoU and both want amendments to some clauses, potentially adding delays. Focus also remains on US diesel policy after Energy Secretary Wright reportedly contacted major refiners to gauge support for voluntarily restricting diesel exports. WTI trades off worst levels and within a USD 92.14-94.75/bbl range, while Brent trades around USD 99.00/bbl within a USD 97.81-99.76/bbl range.
- Dutch TTF is softer alongside the broader pullback in the energy complex, with tentative progress on US-Iran diplomacy helping remove some of the geopolitical risk premium.
- Precious metals are mixed but ultimately contained, with the USD strength this week and the rise global yields continuing to act as headwinds. Spot gold has recovered off worst intraday levels and trades in a USD 4,255-4,296/oz range. Spot silver remains softer around USD 63.72/oz within a narrow USD 63.36-64.08/oz range. Base metals are subdued amid the absence of mainland Chinese participants overnight, with 3M LME copper within a USD 14,615.68-14,701.97/t range at the time of writing.
- EU Commission said that gas supply remains stable; to reconvene on October 8.
TRADE/TARIFFS
- EU urges the UK to increase tariffs on Chinese cars to avoid ‘made in Europe’ barriers, according to FT.
- Chinese President Xi said China and US made common understanding on many issues and that he had frank and in-depth exchange with US President Trump.
- US President Trump said in state dinner for Chinese President Xi that US and China have never gotten along better, adds can continue prosperous and secure future with China.
- US President Trump posted on Truth Social that the state dinner at the White House for Chinese President Xi Jinping will be spectacular.
NOTABLE EUROPEAN DATA RECAP
- European Loans to Households (Aug YY) 3.1% vs. Exp. 3.2% (Prev. 3.1%).
- European M3 Money Supply (Aug YY) 3.5% vs. Exp. 3.5% (Prev. 3.4%).
- European Loans to Companies (Aug YY) 4.2% (Prev. 4.4%).
- Spanish GDP Growth Rate Final (Q2 QQ) 0.7% vs. Exp. 0.7% (Prev. 0.6%).
- Spanish GDP Growth Rate Final (Q2 YY) 2.6% vs. Exp. 2.7% (Prev. 2.7%).
- French Non Farm Payrolls (Q2 QQ) -0.1% (Prev. 0%).
- French Private Non Farm Payrolls Final (Q2 QQ) -0.1% vs. Exp. -0.1% (Prev. -0.1%).
- German GfK Consumer Confidence (Oct) -30.6 vs. Exp. -27.4 (Prev. -26.8).
- UK GfK Consumer Confidence (Sep) -13 vs. Exp. -16 (Prev. -14).
CENTRAL BANKS
- CNB Minutes: Governor Michl emphasises the need to remain hawkish; assessed the current monetary policy stance as appropriate; so far no second-round effects.
NOTABLE US EQUITY HEADLINES
- Anthropic strikes USD 12bln deal with Akami (AKAM) for AI computing.
GEOPOLITICS
RUSSIA-UKRAINE
- Ukraine President Zelenskiy said that the US proposed a "technical meeting" with Ukraine and Russia in UAE; waiting on the date.
- Russia's defense ministry said it bombed a drone assembly site in the Kyiv region.
- Explosion heard near Ukraine's capital of Kyiv after a Russian drone attack.
- US envoys Witkoff and Kushner met with Russia's Dmitriev today, according to CNN.
- Chinese President Xi said North Korea, Middle East and Ukraine was discussed with US President Trump, while Xi and Trump agreed to build a stable China-US relationship.
- Russian and Iranian Foreign Ministers say there is no alternative to a diplomatic solution to the war in Iran, Al Arabiya reported.
MIDDLE EAST
Iranian Commentary:
- IRGC spokesperson warned in the event of another attack, Iran's method of defence will change including geography of the confrontation, the type of equipment and weapons used, and targets in defensive operations in line with new conditions.
- Iranian Brigadier General Sheikh said "we seek to expand our capabilities and reconsider our tactics and technologies", via Al Mayadeen.
Other:
- Yemeni Houthi official warns the coming period will be more painful for Saudi Arabia if its actions against Yemen continue, ISNA reported.
- Israel's channel 12 noted that the army will enter a new phase of fighting in southern Lebanon in the coming days. said:. Army has completed operation to destroy Hezbollah's infrastructure in the Yellow Line area.
- Israeli military will enter a new phase of fighting in southern Lebanon in the coming days, Israeli Channel 12 reported cited by Sky News Arabia. The army completed the process of destroying Hezbollah’s infrastructure in the Yellow Line area.
- Strait of Hormuz's commodity vessel crossings dropped to single digits, according to preliminary ship tracking data.
- Saudi Foreign Ministry said Saudi Arabia, Turkey and Pakistan will hold urgent chiefs of staff meetings to discuss support for Riyadh under the joint defence pact.
- Saudi Arabia's civil defence issues emergency warning for the Jazan province, but announces the danger has passed shortly after.
CRYPTO
- Bitcoin is a touch lower this morning and holds just above the USD 84k mark; Ethereum moves higher, posting gains of c. 1%.
APAC TRADE
- APAC stocks were ultimately mixed following the inconclusive handover from the US, where the major indices finished flat after the bond rout deepened, while conditions were thinned in the region owing to the holiday closures in South Korea, Taiwan and Mainland China.
- ASX 200 was led lower by underperformance in tech and with nearly all sectors in the red aside from financials and consumer staples, while price action was not helped by the lack of catalysts and data releases.
- Nikkei 225 extended on recent momentum and rose above 66,000, while the index was unfazed and Japanese banks were underpinned by a higher yield environment, which saw the 30yr yield at its highest since its debut in 1999.
- Hang Seng suffered despite the pleasantries at the Trump-Xi summit and state dinner, as the meeting of the leaders failed to result in any major breakthroughs, while there were losses in nearly all but a handful of the Hong Kong benchmark's constituents and the Stock Connect was shut due to the closure in the mainland for the Mid-Autumn Festival.
NOTABLE ASIA-PAC HEADLINES
- Japanese Finance Minister Katayama said specific monetary policy tools are up to BoJ to decide and that the central bank will conduct appropriate monetary policy while coordinating with government, adds Trump voiced concerns about yen weakness at summit. said:. Won't comment on specific FX levels or rate checks. Japan will closely coordinate with US on foreign exchange. PM Takaichi expressed concern about the yen’s weakness in general.
- Japanese Economic Minister Kiuchi said not in era to do monetary easing, adds phase of monetary easing and agile fiscal spending ended.
- Chinese VP Han said China willing to work with Serbia to lift bilateral ties to higher levels, according to Xinhua.
- Trump and Xi confirmed that they would support each other in hosting the APEC Economic Leaders' meeting and the G20 summit in 2026, Xinhua reported; new trade arrangements between China and US is good news for the global economy.
The full platform
Have a play with the Newsquawk platform.
Build a watchlist, pop the widgets out, experiment with the filters and sample the squawks. The whole workspace is open to try — no signup, no card. Newsquawk Pro adds the live feed for £24.99 for 7 days.
Free. No signup, no card.
Both market opens, in your inbox.