
Published:
Newsquawk Desk
US Market Open: Crude benchmarks lower despite Trump threatening to blow up all of Iran, but with optimism ahead of the UN General Assembly
0:00--:--
- US President Trump reportedly said on Sunday that he is thinking of "blowing up" all of Iran as he left the Camp David retreat a day early to return to the White House.
- Pakistani Interior Minister travelled to Iran to discuss bilateral relations and cooperation, but it will be unrelated to Iran-US matters.
- German Chancellor Merz vowed to stay on despite a ‘disaster’ in regional elections, with partial results showing his CDU at just under the 5% threshold for parliamentary representation in Mecklenburg-Vorpommern.
- US equity futures gain as "successful" US-China talks boost optimism.
- DXY muted despite softer energy prices; EUR unreactive following German politics.
- Fixed income benchmarks are firmer given the downside in the crude complex (Brent Dec'26 -1.7%).
- Looking ahead, highlights include comments from ECB's Lagarde, Cipollone, Fed's Goolsbee and BoC's Macklem.
SNAPSHOT
EUROPEAN TRADE
EQUITIES
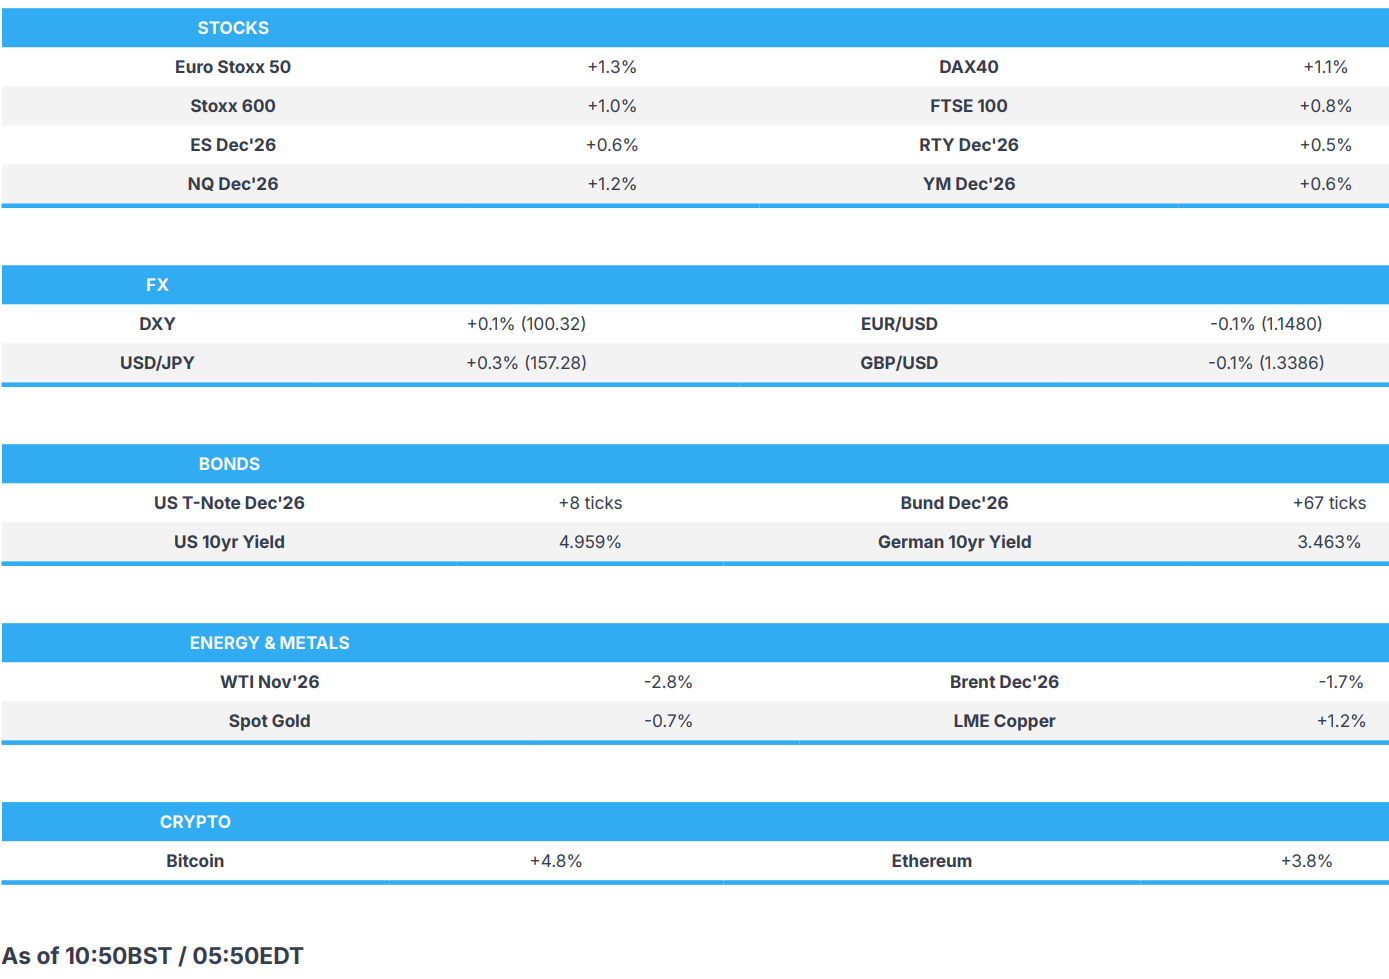
- European bourses (STOXX 600 +1.0%) are firmer across the board, helped by lower energy prices despite heightened geopolitical tensions over the weekend. The Houthis said they attacked sensitive sites in Riyadh and an Aramco facility in Yanbu over the weekend, while US President Trump reportedly said that he is thinking of "blowing up" all of Iran. One source of potential optimism is the commentary following US-China trade talks, with US Treasury Secretary Bessent describing talks as "successful" on trade and AI, while they agreed to hold another meeting on AI dialogue.
- Sectors highlight the positive bias. Tech tops the sector pile, with Industrials and Basic Resources following closely behind. To the downside is Health Care, with Optimised Personal Care and Energy rounding out the sector laggards. Explaining the underperformance in Health Care is the downbeat reaction in Novo shares (-5%) after they announced their 2030 ambitions. The drugmaker plans to launch over 5 blockbusters by the end of 2030 and targets pipeline sales of over DKK 150bln in 2035.
- US equity futures gain, with outperformance in the NQ. Outside of the reasons detailed above, the upside in tech could be influenced by South Korean exports rising 89.8% Y/Y in the first 20 days of September, as semiconductors continue to be the primary driver.
- Click for the sessions European pre-market equity newsflow
- Click for the additional news
FX
- Snapshot: G10s are mixed against a flat USD this morning. The Antipodeans are mildly firmer, benefiting from the risk tone, whilst the Loonie and JPY are the marginal laggards.
- DXY currently holds within 100.20 to 100.37 range, and towards the highs made post-FOMC last week. Newsflow for the Dollar has been lacking this morning; oil prices are slipping off highs, despite ongoing supply disruptions, as attention turns to the UN General Assembly Council this week, alongside the summit between President Trump and Xi. The current mood between the two is positive; Trump recently suggested that he and Xi get on “very well”, whilst Treasury Sec Bessent suggested they had a very successful engagement with the Chinese on trade and AI.
- JPY is a touch lower this morning, giving back some of the strength made last Friday. The Nikkei reported that the BoJ conducted a “rate check” on that Friday, which helped curtail some of JPY pressure seen following the Bank’s dovishly perceived rate decision. This makes evident that the Japanese officials remain ready and active in the market to keep USD/JPY from approaching the 160.00 mark once again. If market expectations of a Fed-BoJ divergence continue to grow, then it may prove to be difficult for Japan to significantly prevent another bout of upside in the pair. Do note that Japan is away on holiday and returns on Thursday; as such, the lower-volume environment could provide a decent opportunity for the MoF to enact some intervention.
- EUR is essentially flat vs USD, despite political uncertainty from within the region. Firstly, two regional elections were held in Germany over the weekend; the ruling CDU party performed terribly, falling short of the 5% threshold to enter state parliament in one state. There is now mounting pressure on current Chancellor Merz to resign, though he announced that he will stay in office and “fight on”. The state election results point out the issues the German population is currently facing, but for now, it will remain a regional problem. It will likely have little impact on the federal government itself; as such, the EUR is little changed.
FIXED INCOME
- USTs (+8 ticks) are stronger this morning, benefiting from 1) falling energy prices and 2) markets awaiting the US-China meeting at the White House on Thursday. On the first point, supply disruptions remain, and Trump recently said he is thinking of “blowing up” all of Iran. It seems as if markets are shifting their attention to the UNGA this week, with Trump reportedly set to meet Gulf leaders and then President Xi. There may be growing hopes that a framework agreement/deal can be ironed out; recent reports have noted that Pakistan’s Interior Minister has travelled to Iran.
- Yields are lower across the curve, with very slight underperformance at the belly. The US 10-year (4.96%) has now slipped below the key 5.00% mark, given the aforementioned energy dynamics. A constructive UNGA mood and/or geopolitical progress could help the 10-year continue to slip to near-term lows, with 4.92% a likely area of support (low from 18 Sep).
- Gilts (+72 ticks) outperform vs peers, and currently hold towards the upper end of an 85.28 to 85.76 range. UK-specific news flow has been focused on pre-budget speculation around housing and CGT, but with action in UK paper today ultimately driven by energy dynamics. On trade relations, UK PM Burnham is set to meet US President Trump this week. Reports suggest that the talks between the pair will focus on the Middle East, energy costs and the ongoing Russia-Ukraine conflict.
- EGBs dominate the fixed income space this morning. Bunds after the latest state parliamentary elections, and OATs after sovereign updates and the latest fiscal disclosure. However, despite these points, EGBs are firmer with the marked energy pullback providing relief and some caveats/points to look to with reference to Bunds and OATs specifically.
- For Germany, the Grand Coalition’s CDU had a disaster in the two elections, while their SPD partner fared somewhat better. Within Mecklenburg-Western Pomerania, the CDU are set to come in below the 5% threshold to enter state parliament, while AfD won with 38.2% but PSD a near second on 35.5%; a point that provides some relief, as there is no appetite to work with AfD, and thus SPD will likely lead a SPD-Green-Die Linke combination of some description in the region. For now, we await the final results of Mecklenburg-Western Pomerania to confirm if CDU has missed the threshold. Thereafter, we look for signs of more pressure on Chancellor Merz and whether the Grand Coalition may look for an alternative to him, a ‘Kanzlertausch’, given the September regional election outcomes and his personal low approval rating.
- Turning to OATs, firstly digesting the trend cut to negative from stable at DBRS, due to “the risk of the government failing to address fiscal imbalances is increasing, leading to a continued rise in the government debt ratio over the medium term”. Additionally, Scope cut France to A+ (prev. AA-), primarily due to the deteriorating fiscal outlook.
COMMODITIES
- WTI Nov and Brent Dec futures are softer after initially advancing at the open on weekend escalation, including a Houthi attack on a Saudi Aramco facility in Yanbu and Trump reportedly saying he was considering “blowing up” Iran. Prices subsequently reversed as the immediate escalation failed to develop further and Trump also signalled openness to meeting Iran’s President. Further, there may be some hopes that the Trump-Xi meeting this week may help simmer down some geopolitical tensions in the Middle East. This morning’s picture remains mixed in terms of newsflow: the IRGC said it shot down a US MQ-1 drone over Hormuz and warned the war “is not over”, while Pakistan’s Interior Minister is heading to Tehran, with conflicting reports over whether the trip involves US-Iran mediation. WTI Nov trades close to the bottom of a USD 93.46-97.22/bbl range, while Brent Dec nearer to the lower end of a USD 96.97-100.22/bbl range. Dutch TTF is sharply softer (-3.8%) alongside the broader pullback in the energy complex within a EUR 76.85-80.55/MWh range.
- Precious metals are softer as the Dollar remains firm in the face of lower oil prices. Spot gold trades around USD 4,350/oz within a USD 4,342-4,383/oz range, and with the 100 DMA at USD 4,319/oz today. Spot silver similarly trades flat on either side of its 100 DMA (USD 66.40/oz) in a narrow USD 65.73-67.05/oz parameter.
- Base metals are firmer despite the cautious broader backdrop, extending some of last week’s gains. COMEX copper trades near the upper end of a USD 6.60-6.66/lb range, and 3M LME copper trades towards the top end of a USD 14,540.50-14,688.00/t parameter, with the complex supported by the generally positive tone across Chinese markets ahead of the Trump-Xi summit and after constructive US-China trade discussions in New York.
- Kazakhstan oil shipments to Ust-Luga were recorded at 200k metric tons in August, according to Interfax.
- French Finance Minister Lescure said France’s strategic oil stocks are full.
- Naftogaz said ORLEN (PKN PW) will supply up to USD 500mln of petroleum products to Ukraine to stabilise the market and deliver three LNG cargoes in Q1 2027.
- South Africa's Pretoria is reportedly looking to leverage its role as a platinum supplier to help integrate into the US and China, Semafor reported.
TRADE/TARIFFS
- US Treasury Secretary Bessent said they had a very successful engagement with the Chinese on trade and AI, while they agreed to hold another meeting on AI dialogue and the US suggested a notification system between the two countries. Bessent separately commented that he is likely to meet the Chinese delegation in two months and they discussed extending the trade truce, although no pact was reached, according to FT citing an interview following Bessent's meeting with Vice Premier He Lifeng.
- USTR Greer said they implemented a board of trade, with the US and Chinese teams to continue working on a board of trade agreement, while the board of trade from the Chinese side is likely to include consumer goods and low-tech items.
- China's top trade negotiator Li said trade talks are ‘not bad’ and that talks will continue on Monday among the working group, while he confirmed that both sides discussed AI along with trade and investment.
- Chinese state media noted that China and the US conducted frank, in-depth and constructive exchanges on important economic and trade issues of mutual concern, while they held dialogue on issues related to AI.
- US and China were reported on Friday to be discussing cutting tariffs on US LNG ahead of Xi's visit, with potential USD 30bln reciprocal tariff cuts, while the visit could bring broader energy and agricultural deals.
- China reportedly purchases more US soy cargoes ahead of the President Trump-Xi meeting.
- Indian Trade Minister said a trade agreement with New Zealand will provide duty-free access to New Zealand for 100% of India's exports.
NOTABLE EUROPEAN HEADLINES
- German Chancellor Merz vowed to stay on despite a ‘disaster’ in regional elections with partial results showing his CDU at just under the 5% threshold for parliamentary representation in Mecklenburg-Vorpommern, while the centre-left SPD is projected as 35.5% of votes and the far-right AfD is expected to get 37.0% of votes, according to exit polls. Merz's conservatives are projected at 20% of votes in the Berlin state election, while the Left Party is seen at 24.5%, SPD is seen at 12%, and AfD is seen at 16% in Berlin.
- Scope downgraded France’s long-term ratings to 'A+' from 'AA-' and revised the outlook to stable; DBRS affirmed France at 'AA', lowered the French outlook to negative.
NOTABLE EUROPEAN DATA RECAP
- UK Rightmove House Prices MM (Sep) 0.7% (Prev. -2.0%).
- UK Rightmove House Prices YY (Sep) -0.8% (Prev. -1.0%).
CENTRAL BANKS
- Fed's Kashkari (2026 voter) said inflation remains too high and that price pressures have expanded beyond the oil-price shock from the Iran war and are affecting the broader economy.
NOTABLE US HEADLINES
- DBRS affirmed the US at AAA, with a Stable Trend.
GEOPOLITICS
MIDDLE EAST
- US President Donald Trump reportedly said on Sunday that he is thinking of "blowing up" all of Iran as he left the Camp David retreat a day early to return to the White House, while Fox News reporter Yungst said Trump told him during a phone call that "very big things are going to be happening" soon. Furthermore, Trump said his options are ‘wiping out’ the regime, letting it ‘rot economically’ under naval blockade, or striking a deal, according to Fox News and The Telegraph.
- US President Trump said on Friday that the Iran War will end soon, adding that once the war ends, US gasoline prices will revert to prior levels and could even fall further. US President Trump confirmed on Friday the US is talking to the Houthis, saying they want a deal, while adding "we'll see" on whether to annihilate Iran.
- US CENTCOM commander Cooper said oil and LNG shipments through the Strait of Hormuz in the past two weeks reached the highest levels in six months. More US troops had reportedly died amid the Iran war than the Pentagon disclosed publicly, according to a report on Friday in the Washington Post.
- Pakistani Interior Minister travelled to Iran today, IRNA reported. Tasnim later reported that the trip is unrelated to Iran-US matters and will focus on bilateral relations and cooperation, with the report adding that Pakistan is not carrying a message between Iran and the US.
- Iranian officials conveyed their conditions to mediators for re-engaging in negotiations for ending the war with the US, while the conditions include ending the war on all fronts and the naval blockade, as well as unfreezing Iranian funds and they also want an end to the war between Saudi Arabia and Yemeni Houthis.
- IRGC spokesman said all of the US' superior technologies pale in comparison to Iran's offensive and defensive capabilities, adding that Tehran are defining the new regime in the region, not America, and the war is not over and continues. The spokesman added that the IRGC has prepared itself for a long-term war and that they have new targets and weapons ready if the US launches a new attack.
- IRGC said it shot down a US MQ-1 drone over the Strait of Hormuz.
- UKMTO received a report of an incident involving a vessel transiting the Strait of Hormuz, reported at 07:30 UTC. A tanker conducting an inbound transit was struck by an unknown projectile.
- Qatar's PM Al-Thani said Gulf states need to cooperate to restore regional stability and help reach a settlement between the US and Iran. It was separately reported that Qatar's Energy Minister said US Treasury Secretary Bessent is "wrong" in saying that the strategic Strait of Hormuz will be worthless in two years.
RUSSIA-UKRAINE
- Russia's Press Secretary Peskov said there have been no progress in negotiations on Ukraine yet but remains open to further talks, IFX reported.
- UK Burnham hopes to build bridges with US President Trump at their first meeting and wants to press the case for the US to help Ukraine with air-defence systems.
- Moscow Oil Refinery was hit during a drone attack that was part of Ukraine's largest barrage this year.
OTHER
- US, Denmark and Greenland reached a security agreement that expands the US’s role on the Arctic island to end the row that threatened NATO.
- North Korea launched two missiles off its eastern coast on Sunday. It was also reported that North Korea rejected an IAEA resolution on its nuclear program and vowed to keep its status as a nuclear-armed state.
- Japanese Defence Minister Koizumi and US Defence Secretary Hegseth agreed in a phone call to further strengthen security ties.
CRYPTO
- Bitcoin surges at the start of the European session and has regained the USD 85k mark, having started the session just above the USD 81k handle. Despite a clear driver, some reports point to Russia holding talks with major banks and financial firms to expand access to the crypto market.
APAC TRADE
- APAC stocks were ultimately mixed, but with cautious gains seen for most of the region ahead of this week's key meetings in the US, including the UN General Assembly and the Trump-Xi summit, while there are also thinned conditions with the closure of Japanese markets through to Wednesday.
- ASX 200 was uneventful amid mixed M&A related headlines and further RBA rate hike calls, with CBA bringing forward its rate hike call to September from November, while ANZ expects hikes in both September and November.
- KOSPI outperformed as tech stocks took impetus from the advances in the Nasdaq last Friday.
- Hang Seng and Shanghai Comp were mildly higher ahead of the Trump-Xi summit this week and after US and Chinese officials held talks in New York ahead of the leaders' meeting, with China's top trade negotiator describing the discussions as 'not bad', while state media noted the sides had frank, in-depth and constructive exchanges on important economic and trade issues of mutual concern, as well as holding dialogue on AI-related issues.
NOTABLE ASIA-PAC HEADLINES
Japan's government will work with major machinery manufacturers to collect machine-learning data for physical AI applications such as autonomous robots and assigning unique IDs to factory equipment to enable cross-vendor data aggregation, according to Nikkei.
Japan is poised to ease restrictions on regional bank loans for AI and energy projects, Nikkei reported.
China's CPC Politburo met to discuss draft documents to be submitted to the Fifth Plenary Session (26th-29th October), with Chinese President Xi presiding.
NOTABLE APAC DATA RECAP
- Chinese 1-Year Loan Prime Rate (Sep) 3.00% vs. Exp. 3.00% (Prev. 3.00%).
- Chinese 5-Year Loan Prime Rate (Sep) 3.50% vs. Exp. 3.50% (Prev. 3.50%).
- South Korea September 1st-20th Exports rose 78.3% Y/Y, Imports rose 26.7% Y/Y, Trade Balance at a provisional surplus of USD 22.97bln.
The full platform
Have a play with the Newsquawk platform.
Build a watchlist, pop the widgets out, experiment with the filters and sample the squawks. The whole workspace is open to try — no signup, no card. Newsquawk Pro adds the live feed for £24.99 for 7 days.
Free. No signup, no card.
Both market opens, in your inbox.