
Published:
Newsquawk Desk
US Market Open: Crude benchmarks gain on punchy IRGC rhetoric, which lifts yields to multi-year highs; US-China meeting ahead
0:00--:--
- Senior adviser to Iran’s Supreme Leader Major General Safavi said the scope of the war may expand to the Indian Ocean and other regions, if the US starts a new war.
- US Treasury Secretary Bessent announced a two-month extension to the trade truce with China, extending to January 10th.
- A flurry of Central Bank announcements; SNB and Riksbank hold while the Norges Bank hiked by 25bps to 4.50%.
- Global equities are under pressure amid the hawkish comments by Iranian officials, which has lifted the energy complex (Brent +2.1%).
- DXY makes fresh WTD highs as US yields remain at elevated levels (US 10yr yield 5.15%).
- Looking ahead, highlights include US Initial Jobless Claims, Chinese President Xi's state visit to the US, Banxico Policy Announcement. Speakers include Fed's Barkin, Hammack & Paulson, BoE's Breeden & Lombardelli. Supply from the US.
SNAPSHOT
EUROPEAN TRADE
EQUITIES
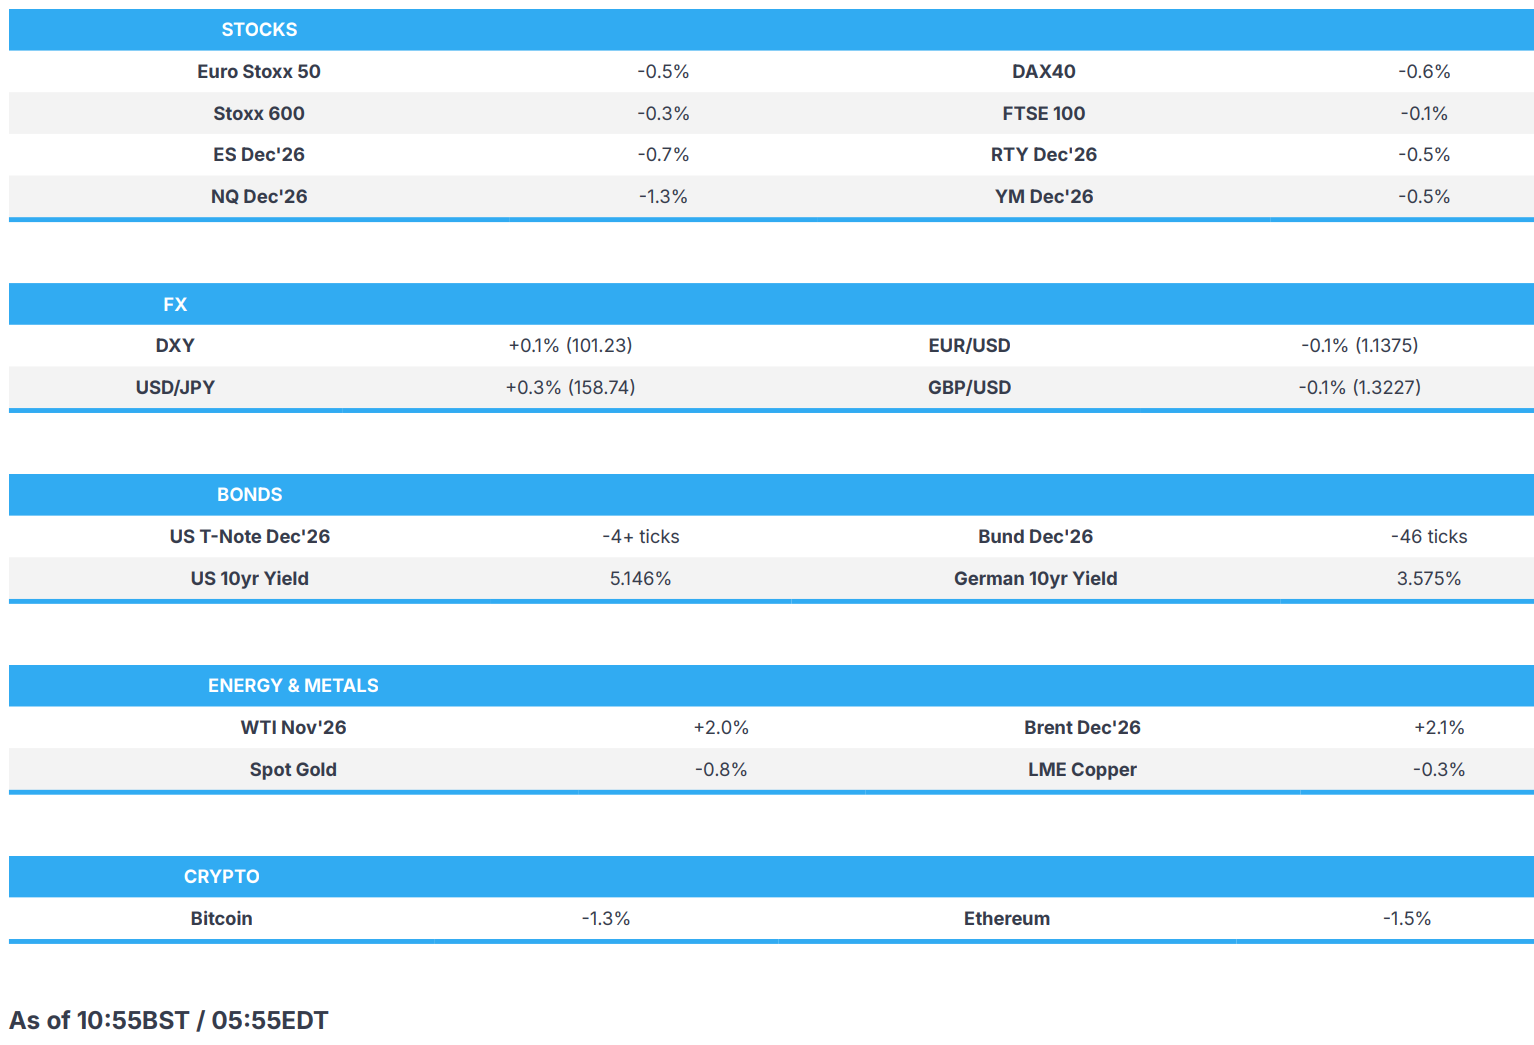
- European bourses (STOXX 600 -0.3%) opened entirely in the red and has come under a fresh leg of pressure in recent trade amid the upside across the energy space. The source of the move came amid comments by the Senior adviser to Iran’s Supreme Leader Major General Safavi, saying the US conflict could expand further into the Indian Ocean.
- Sectors highlight the negative bias. Energy, Food, Beverages & Tobacco and Optimised Personal Care are the only sectors in the green. Leading the downside is Tech, followed by Autos and Financial Services.
- US equity futures have extended on Wednesday's losses, following the broader equity space as sentiment continues to sour. The Trump-Xi meeting will be one to watch on today's calendar, following US Treasury Secretary Bessent's announcement of a two-month extension to the trade truce.
- Click for the sessions European pre-market equity newsflow
- Click for the additional news
FX
- G10s are mostly lower against the USD, albeit only marginally. The EUR holds afloat, joined by the Kiwi, Loonie and GBP, whilst the CHF underperforms a touch.
- DXY holds within a 101.00 to 101.23 range. The Dollar traded steady throughout overnight and early-European trade, but then moved higher alongside a bout of strength in the energy complex. This came after an IRGC official noted that the “war could expand” to the Indian Ocean or Bab el Mandeb Strait if the US decides to go to war again. More generally, crude benchmarks will be digesting reports that the US dismissed Iran's Hormuz offer during UN talks, saying Tehran does not control the Strait.
- Fed’s Williams spoke this morning, where he suggested it was reasonable to see another rate hike by year-end. Markets are pricing in a 38.4% chance of one 25bps hike by year-end, with a c. 50% chance of another this year.
- Policy announcements from the SNB, Riksbank and Norges Bank have led to some volatility in the respective currencies. Kicking off with SNB, the Bank opted to hold rates, lifted inflation projections and removed its “increased willingness” for intervention. As such, the CHF moved lower following the announcement. Over in Sweden, the SEK was initially choppy following the Bank’s decision to hold rates. But then gradually strengthened, as the Bank lifted its rate path forecasts to imply a hike towards the end of this year/start of next year. Elsewhere, the only hike today was delivered by Norges Bank. It lifted its Key Policy rate by 25bps to 4.50%, and reiterated its tightening bias. EUR/NOK knee-jerked lower as traders unwound their bets of a hold, before paring around half of that move.
FIXED INCOME
- The very modest bearish action at the start of the morning has given way to downside of c. 40 ticks in Bunds. Amidst a combination of factors, namely: energy upside on Iranian commentary, hawkish central banks, strong German Ifo & trade/tariff concern ahead of the US-China meeting, and also from Germany via the VDA.
- Unsurprisingly, the bulk of the move was on the Iranian adviser Safavi intimating that the “scope of the war may expand…”, to include the Indian Ocean and other regions. An update that, over the course of around one hour, lifted Brent by over USD 2.00/bbl and pushed the US 30yr yield to its highest in over 20 years.
- Bunds hit a 119.87 trough, nine ticks above Wednesday’s contract low. As mentioned, much of the focus has been on yield action, with upside seen across curves globally and a slightly steepening bias seen.
- For USTs, no real move to Fed’s Williams, though he did note that pricing for another hike by end-2026 is “reasonable”. As it stands, markets imply a 38% chance of one 25bps hike by year-end, and just over a 50% chance of two. At a 104-28 contract low with yields bid across the curve.
- Ahead, the focus remains on central banks with several speakers due, before the Trump-Xi meeting begins and the readout which is scheduled for just after 15:00BST commences. A meeting that is framed by recent remarks from Treasury Secretary Bessent that while the truce has been extended to January 2027, he does not know if a bigger deal can be done.
- Italy sells EUR 2.5bln vs Exp. 2.5-3bln 3.00% 2028 BTP: b/c 1.64x (prev. 1.58x), average yield 3.64% (prev. 3.02%).
COMMODITIES
- WTI Nov and Brent Dec futures started the European morning with only modest gains, but gradually picked up as the session progressed. The bullish bias potentially comes amidst the lack of US-Iran diplomatic progress and after an IRGC official noted that the “war could expand” to the Indian Ocean or Bab el Mandeb Strait if the US decides to go to war again.
- Focus also remains on the potential US diesel export ban, although the White House denied reports that the Trump administration is preparing a 90-day ban. Morgan Stanley warned that such a move, while not its base case, could have significant implications and potentially raise gasoline prices as barred diesel exports fill storage and force refiners to cut runs. The bank estimated refiners could need to reduce runs by around 2mln BPD, in turn cutting gasoline supply by roughly 650k BPD.
- WTI trades around USD 93.70/bbl within a USD 91.23-94.69/bbl range, while Brent trades above USD 100.00/bbl within a USD 97.09-100.94/bbl range. Dutch TTF is firmer, with the contract trading within a EUR 73.39-75.04/MWh range. The Trump-Xi meeting could provide some impact amid reports of potentially reducing or removing China’s 15% tariff on US LNG.
- Precious metals remain subdued following Wednesday’s surge in the USD and global yields, with hawkish Fed rhetoric and strong US data continuing to weigh on the complex. Spot gold trades towards the bottom of a USD 4,254-4,303/oz range, with the 100 DMA at USD 4,309/oz. Spot silver similarly trades around the lower end of a USD 63.52-64.55/oz range.
- Base metals are mixed/rangebound against a subdued risk backdrop, with copper also digesting news that BHP suspended operations at its Escondida mine in Chile following an accident. 3M LME copper resides in a USD 14,575.08-14,677.78/t range.
- Saudi Aramco CEO said that it is studying a "a fourth and a fifth route" for crude oil exports and noted that the Co. can restore disrupted operations within days.
- China’s NDRC raised retail fuel prices in the current bi-monthly cycle, effective September 25th, with gasoline prices up CNY 395/tonne and diesel prices up CNY 385/tonne.
- BHP (BHP AT) said operations at the Escondido mine in Chile were suspended following an accident.
TRADE/TARIFFS
- US President Trump said it was a great greeting with Xi and that the entire tech and banking world will be at Thursday's dinner. Trump also stated that he had some great conversations with leaders at the UN General Assembly.
- Chinese President Xi said he looks forward to in-depth exchanges with US President Trump and will expand cooperation between the two countries in various areas, while he is confident the US trip will produce fruitful results. Xi also commented that China and the US must be allies, not adversaries, and he is confident China and the US can find the right path to coexist in a new era.
- US Treasury Secretary Bessent said the US-China trade truce was extended to January 10th, while he doesn't know if a bigger trade deal can be done with China and could just roll the current deal forward. Furthermore, Bessent said that presidents Trump and Xi are expected to meet four times this year and that China is doing well so far in meeting 2026 pledges.
- China's MOFCOM said they discussed AI with the US under the bilateral economic and trade consultation mechanism.
- Germany's VDA is reportedly endorsing new tariffs against China for the first time, according to Handelsblatt.
- India cut import duties on crude palm oil and soybean oil to 5% (prev. 10%).
NOTABLE EUROPEAN HEADLINES
- The UK Treasury is open to smaller fiscal headroom and Chancellor Healey may accept a smaller fiscal buffer to reduce tax rises in next month’s Budget, according to FT.
NOTABLE EUROPEAN DATA RECAP
- German Ifo Expectations (Sep) 90.4 vs. Exp. 89.3 (Prev. 89.1).
- German Ifo Current Conditions (Sep) 89.5 vs. Exp. 89 (Prev. 88.5).
- German Ifo Business Climate (Sep) 89.9 vs. Exp. 89 (Prev. 88.8).
- French Business Confidence (Sep) 101 vs. Exp. 102 (Prev. 101).
- French Consumer Confidence (Sep) 86 vs. Exp. 85 (Prev. 86).
CENTRAL BANKS
- Norges Bank hiked rates by 25bps to 4.50%. Expectations heading into the announcement were split. The Bank noted that inflation has been above target for several years, and that by raising the rate, it will help reduce inflation and that the policy rate will be elevated for a time. The Committee is prepared to raise the policy rate further if warranted by the inflation outlook. The decision was backed by continued elevated inflation metrics, with the Bank alert to upward risks to the inflation outlook; it stated that "Inflation may then become stickier and harder to bring down again". Governor Bache suggested that the inflation outlook has not materially changed, as such, stated that the Bank is prepared to deliver further rate hikes to bring inflation down to target. This is reflected in the rate path projection, which does not point to further tightening later this year, but will continue into Q1/Q2'27.
- The Riksbank left rates unchanged at 1.75%, as expected. With the commentary, and particularly the forecasts, a hawkish bias can be seen with the language being that "it is expected that the increases to the policy rate will begin this year", while the forecasts imply a hike around end-2026/start-2027 and then another one in the Q2/Q3-2026 period, and then thereafter there is some optionality of another hike by Q3-2028, a marked hawkish tilt vs the June projections. Albeit, this is caveated by the assessment that Q2 GDP strength was somewhat due to temporary factors, though the general commentary remains constructive. Overall, the strengthening of the SEK highlighted the overall hawkish tone.
- The SNB left rates unchanged at 0%, as expected. The main update was the tweak to the FX language, which now shows "...willing to be active in the foreign exchange market..." from the June line of "If necessary, the SNB has an increased willingness to intervene in the foreign exchange market", omitting the "increased" framing. In terms of the Bank's inflation forecast, they were lifted across 2026, 27 and 28, primarily due to higher energy prices. They also noted that the recent uptick in inflation was attributed to a rise in goods inflation, driven by higher prices for oil products. In an immediate reaction, the CHF weakened given the aforementioned change to the intervention language.
- Fed's Williams (voter, Neutral) said the big challenge is on inflation and need to get it back to target in a timely manner while stating that it is reasonable to see another rate hike by year-end. He said short-run inflation expectations have been more encouraging, though the longer term they have not. On the economy, Williams said it has been remarkably resilient and downside risk to achieving maximum employment have receded.
- BoE's Lombardelli said policy is increasingly likely to need to tighten if elevated energy prices persist. On second-round effects, she said the absence of evidence is something but not much, and that it is likely still too early to see evidence in the data. On policy, Lombardelli described it as restrictive and that it is increasingly likely to need to tighten if elevated energy prices persist, absent clear evidence of disinflation or weaker activity.
- BoE's Dhingra said most of the financial conditions have done a lot of tightening work already in the UK and is encouraged on what pricing is doing. Dhingra added that the labour market looks pretty weak, while highlighting that winter energy prices will be critical for second round effects.
- ECB’s Kocher said the ECB must prevent excessively high inflation from becoming entrenched and that the Eurozone economy remains fragile. Kocher added that there has been signs of somewhat more Eurozone momentum since summer.
- ECB's Schnabel said the energy shock is much more persistent than thought.
NOTABLE US HEADLINES
- A US judge issued an order blocking the Trump administration’s White House ban on CNN, MS NOW and Politico.
- US Senate Majority Leader Thune believes President Trump is open to implementing AI guardrails despite his public defiance on the issue, according to Axios.
- BofA Total Card Spending (w/e Sep 19th) +6.9% Y/Y (prev. +5.8% W/W); surging gas prices have opened up a gap in ex-gas spending between higher and lower income households.
- An industry group representing US tech companies is reportedly pushing the US administration to withdraw its proposal to charge for H-1B visas, according to the WSJ.
GEOPOLITICS
MIDDLE EAST
- Senior adviser to Iran’s Supreme Leader Major General Safavi said the scope of the war may expand to the Indian Ocean and other regions, if the US starts a new war.
- Israeli source said an additional round of strikes against Iran seems to be a matter of time, Al Hadath reported. The source added that Iran is intensifying the transfer and fortification of the Natanz nuclear project. Additionally, the source said Israel does not see a real chance of reaching an agreement between the US and Iran, and that the US wants to end the Iran war with a political agreement or a decisive attack that topples the regime. On further strikes, the Israeli source said they will strike Iranian nuclear facilities again if Iran crosses the red lines, with or without US involvement.
- US Treasury Secretary Bessent said they are getting sometimes up to 17mln oil barrels out of Hormuz and noted that probably 80-90% of Iran's external flights are shut down.
- Chinese Foreign Minister said the Strait of Hormuz conflict must be resolved through dialogue and calls on all parties to seek a peaceful solution, Al Arabiya reported.
- Pakistan's Foreign Minister told Iran's Foreign Minister that they must remain committed to dialogue and diplomacy.
- Iran's Foreign Ministry noted that Iran's Foreign Minister held a meeting with Pakistani counterpart at the UN General Assembly.
- UK Chancellor Healey said he spoke with US Treasury Secretary Bessent today about stepping up pressure on Iran and how to work together to drive growth in both nations.
- EU's Costa spoke to Iran's President Pezeshkian and urged Iran to resume its cooperation with the IAEA, while he also called for an end to Iran's strikes against its neighbours and a full restoration of freedom of navigation in the Strait of Hormuz.
- Initial reports noted two explosions in Bandar Abbas and one in Sirik, southern Iran, with the explosion in Sirik reportedly coming from near the coast, off to the sea.
RUSSIA-UKRAINE
- Russia's Kremlin said no decision yet has been made on a December summit between US President Trump and Russian President Putin and that discussing a possible agenda is premature.
- Waves of Russian missiles attacked Kyiv and more than a dozen heavy explosions were heard in 30 minutes, according to an FT reporter.
OTHER
- North Korean Foreign Minister said denuclearisation is an unrealistic delusion and that their nuclear status is irreversible, which will endure forever, while he added that the more the US and its allies advocate denuclearisation, the more they will strengthen their stance towards the US.
CRYPTO
- Bitcoin extends on Wednesday's trough of USD 83.5k and has fallen to a low of USD 82.7k amid the rise in energy prices.
APAC TRADE
- APAC stocks were mostly pressured following on from the declines in global peers alongside the recent bond turmoil and jump in yields, owing to several factors including strong US data, hawkish Fed rhetoric and mixed reports regarding a US diesel export ban.
- ASX 200 retreated with the declines led by weakness in miners, real estate and materials, while sentiment was not helped by mixed jobs data including an unexpected rise in the Unemployment Rate to a five-year high.
- Nikkei 225 outperformed after Japanese participants returned from the long weekend and with tech names playing catch-up to the recent AI-related momentum.
- Hang Seng and Shanghai Comp retreated despite early optimism from President Xi's state visit to the US, while a two-month extension to the US-China trade truce until January 10th also failed to spur risk appetite.
NOTABLE ASIA-PAC HEADLINES
- PBoC will offer lenders a record amount of up to CNY 1tln in overnight funds each day over the upcoming holiday period, according to Bloomberg.
- PBoC to comprehensively use and timely adjust monetary policy tools to keep liquidity ample; to step up counter cyclical adjustments.
- Japan's Finance Ministry is to consider cutting issuances in liquidity-enhancement auctions for medium-term JGBs, according to sources.
- Japanese Finance Minister Katayama said the principles on forex established since the joint US-Japan intervention remain in effect, while she won't comment on specific FX levels.
- Japan reportedly plans to finance economic security spending mainly through "bridging bonds", reducing the need for the issuance of deficit bonds, Nikkei reported citing sources.
NOTABLE APAC DATA RECAP
- Australian Employment Change (Aug) 39.5K vs. Exp. 20K (Prev. -15.8K).
- Australian Unemployment Rate (Aug) 4.6% vs. Exp. 4.5% (Prev. 4.5%).
- Australian Participation Rate (Aug) 67.1% vs. Exp. 66.9% (Prev. 66.9%).
- Japanese Global Composite PMI Flash (Sep) 52.5 (Prev. 53.5).
- Japanese S&P Global Manufacturing PMI Flash (Sep) 54.1 vs. Exp. 55 (Prev. 54.9).
- Japanese Global Services PMI Flash (Sep) 51.6 (Prev. 52.5).
The full platform
Have a play with the Newsquawk platform.
Build a watchlist, pop the widgets out, experiment with the filters and sample the squawks. The whole workspace is open to try — no signup, no card. Newsquawk Pro adds the live feed for £24.99 for 7 days.
Free. No signup, no card.
Both market opens, in your inbox.