
EU Market Open: APAC stocks were mostly lower, and European bourses set for a negative cash market open; DXY mildly pressured
Newsquawk Analysts ·
Listen
0:00--:--
- Iran’s IRGC destroyed a US MQ-9 drone over the Strait of Hormuz; separately, Sabereen reported that explosions were heard in Bandar Abbas, though details were light.
- Crude benchmarks are mildly firmer amidst the tense geopolitical environment; the Pakistani Army Chief is set to arrive in Tehran today.
- APAC stocks were mostly lower; European equity futures are set for a lower open.
- G10s are mildly firmer against the softer USD; the Kiwi marginally leads.
- Fixed benchmarks are mixed; JGBs soar following a stellar 20-year auction.
- Looking ahead, highlights include German PPI (Sep), UK Unemployment Rate (Aug), EU/German ZEW Survey (Oct), US Building Permits (Sep), NBH Policy Announcement. Speakers include BoE's Greene & RBA's Hauser, Supply from the UK & Germany. Earnings from EssilorLuxottica, ABB, GE Aerospace, General Motors, RTX, Northrop Grumman, Netflix & United Airlines.
SNAPSHOT
- Highlights include German PPI (Sep), UK Unemployment Rate (Aug), EU/German ZEW Survey (Oct), US Building Permits (Sep), NBH Policy Announcement. Speakers include BoE's Greene & RBA's Hauser, Supply from Japan, UK & Germany. Earnings from EssilorLuxottica, ABB, GE Aerospace, General Motors, RTX, Northrop Grumman, Netflix & United Airlines.
- Click for the Newsquawk Week in Focus.
US TRADE
EQUITIES
- US stocks rebounded to start the week as AI concerns eased over the weekend, although breadth was poor outside of AI names. Hyperscaler and mega-cap names drove gains within Tech and Consumer Discretionary (AMZN +5%, named a top pick at MS), while Utilities, Real Estate and Financials lagged (RSP -0.2% vs. SPX +0.6%). In the final hour, Bloomberg reported that Nscale is in talks with Anthropic for a USD 45bln cloud computing deal, which lifted neocloud names, although CoreWeave finished 0.4% lower despite positive sell-side commentary.
- SPX +0.63% at 7,708, NDX +1.17% at 29,529, DJI +0.07% at 52,041, RUT +0.37% at 2,731.
- Click here for a detailed summary.
NOTABLE HEADLINES
- US President Trump posted that American incomes have reached record highs, employment and exports are at all-time highs, and the US is now the "hottest" country in the world.
APAC TRADE
EQUITIES
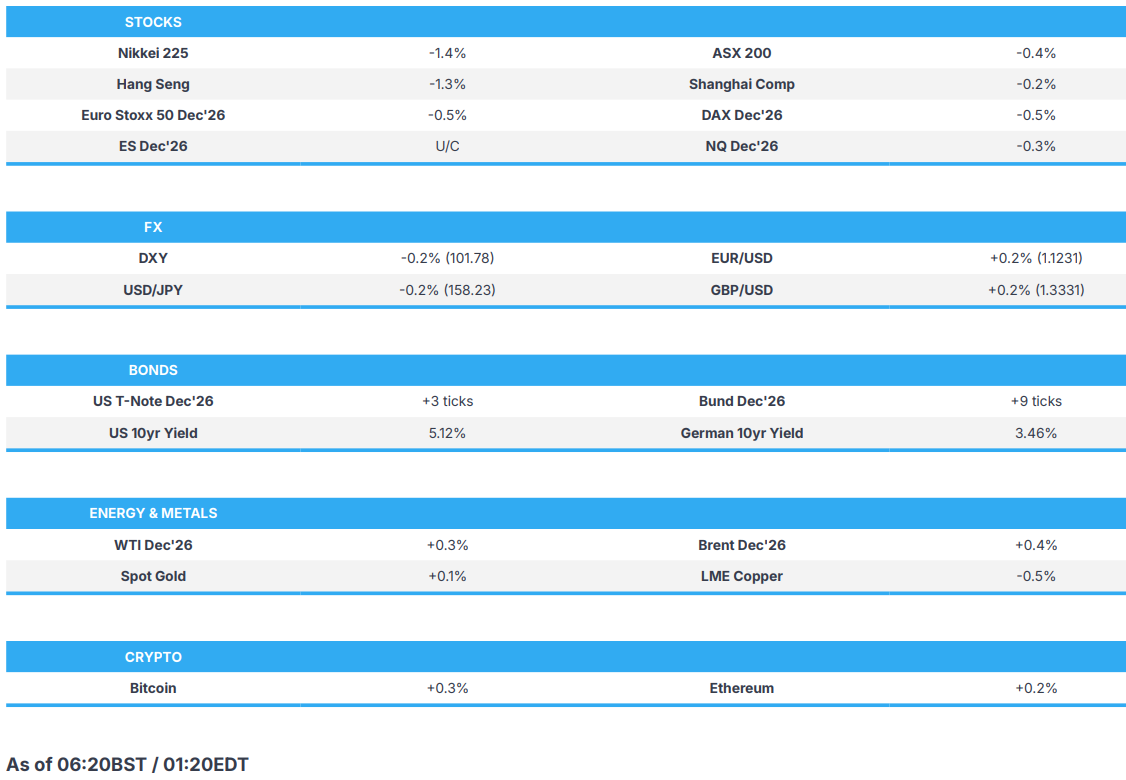
- APAC stocks were mostly lower despite the rebound on Wall Street, as the region failed to sustain the AI-led recovery, with chip-heavy markets in South Korea and Japan underperforming but macro newsflow rather light.
- ASX 200 declined, with gold miners pressured following Monday's pullback in the precious metal, while financials were in focus after S&P downgraded Bank of Queensland's long-term rating to BBB+ from A-, and Westpac flagged an AUD 41mln notable item related to RAMS litigation.
- Nikkei 225 was subdued as tech names failed to benefit from the AI-led rebound stateside, although the index pared some of its earlier losses of over 1%. SoftBank was in focus following reports that it is in discussions to participate in OpenAI's private funding round ahead of Anthropic's IPO.
- KOSPI was the regional laggard, extending its October rout, with Samsung Electronics and SK Hynix pressured amid reports that US big tech firms are pushing for lower memory prices by citing Chinese suppliers as alternatives.
- Hang Seng and Shanghai Comp diverged, with Hong Kong lower as it returned from Monday's Chung Yeung holiday, while the mainland was flat as Chinese LPRs were maintained, as expected.
- US equity futures were modestly firmer, with ES and YM edging higher following Monday's AI-led gains, while NQ was little changed.
- European equity futures indicate a negative cash market open, with Euro Stoxx 50 futures down 0.5% after the cash market closed with losses of 0.9% on Monday.
FX
- DXY drifted lower to fresh APAC session lows beneath 101.90 despite a lack of fresh newsflow, as G10 peers edged to session highs. There is no tier-1 US data scheduled this week and the Fed is in its blackout period ahead of next week's meeting, leaving geopolitics and the AI trade as the main drivers.
- EUR/USD edged higher within a 1.1211-1.1230 range, benefiting from the softer dollar, though remains close to the 1.1200 handle after the single currency underperformed on Monday amid civil unrest in France and other European cities. Focus is also on Moody's review of France on Friday.
- GBP/USD was firmer and reclaimed the 1.3300 handle to trade in a 1.3304-1.3330 range, with attention on UK unemployment data later today. The Times reported that Chancellor Healey has ruled out raising capital gains tax in the 28th October Budget.
- USD/JPY was marginally lower within a 158.36-158.60 range, with markets on watch for potential jawboning as the pair holds above 158.00. Japanese Finance Minister Katayama said no decisions have been made on funding defence spending increases, while Economy Minister Kiuchi said he hopes to attend this month's BoJ policy meeting.
- Antipodeans edged higher alongside G10 peers amid the softer dollar.
- PBoC set USD/CNY midpoint at 6.7200 vs exp. 6.6813 (prev. 6.7208).
FIXED INCOME
- 10yr UST futures were little changed within a 105-05 to 105-09+ range, following Monday's decline as the easing of AI concerns prompted a return of the Treasury sell-off, alongside gains in front-month crude futures on unconfirmed Houthi attacks on Saudi oil facilities.
- Bund futures were marginally firmer in quiet overnight trade within a 121.07-121.23 range, following Monday's pressure across European fixed income amid the civil unrest in France, which saw the OAT-Bund 10yr spread widen to around 145bps ahead of Moody's review on Friday. German PPI and the ZEW survey are due later.
- 10yr JGB futures reversed earlier losses to trade flat amid a strong 20yr JGB auction which saw the strongest demand for the line on record.
- Japan sold JPY 700bln 20yr JGB; b/c 5.84x (prev. 4.01x), average yield 3.7230% (prev. 3.8560%), tail 0.07 (prev. 0.15).
COMMODITIES
- Crude futures were modestly firmer, with WTI Dec just under USD 99.00/bbl (98.04-99.00 range) and Brent Dec around USD 110.00/bbl (109.00-110.17 range), supported by continued geopolitics, as the IRGC said it intercepted and destroyed a US MQ-9 drone over the Strait of Hormuz, an explosion was reportedly heard in Bandar Abbas, and Yemeni forces reportedly targeted Saudi Arabia's Dammam airport. Meanwhile, Pakistani Army Chief Munir is due to arrive in Tehran today.
- Spot gold was modestly firmer around USD 4,150/oz, recovering from an earlier low of USD 4,116/oz as the dollar softened; spot silver outperformed with gains of 0.7%.
- Copper futures were marginally firmer but then succumbed to selling pressure, with 3M LME copper around USD 14,325/t.
- US Energy Secretary Wright said no Russian Diesel has been released yet and yet to be seen if Russia will release diesel.
- Ukrainian President Zelensky said Ukraine could stop striking Russian refineries in return for the US helping with patriot missiles for this period; Decisions taken by the US side are "hard to explain".
- US Energy Secretary Wright said talks with the UK on diesel stock releases are continuing; The US is converting sanctioned tankers to legitimate tankers. Dozens to hundreds of dark tankers could be converted.
CRYPTO
- Bitcoin was slightly lower around USD 81,800, with price action contained in quiet overnight trade.
CENTRAL BANKS
- Japan's Economy Minister Kiuchi said he hopes to attend this month's BoJ policy meeting if his schedule allows.
- PBoC will conduct overnight reverse repos from October 21st to November 2nd via fixed-rate, quantity-based tenders, capped at CNY 1tln daily, and will include foreign-invested RMB settlement banks among eligible counterparties.
- Chinese Loan Prime Rate 5Y (Oct) 3.5% vs. Exp. 3.5% (Prev. 3.5%).
- Chinese Loan Prime Rate 1Y (Oct) 3.0% vs. Exp. 3.0% (Prev. 3.0%).
NOTABLE ASIA-PAC HEADLINES
- China's NDRC said it will introduce additional policy measures as needed to keep economic activity within a reasonable range.
- Japanese Finance Minister Katayama said no decisions have been made on funding defence spending increases, but measures to secure stable funding will be considered while maintaining fiscal sustainability.
GEOPOLITICS
RUSSIA-UKRAINE
- Trump administration has delayed approving transfers of Patriot interceptor missiles to Ukraine from partner countries, Washington Post reported.
- US President Trump's envoys Kushner and Witkoff plan to travel to Norway this week for Ukraine talks and Ukraine President Zelensky is expected to join talks.
MIDDLE EAST
- Iran's IRGC said it intercepted and destroyed a US MQ-9 drone over the Strait of Hormuz using its new advanced air defence system.
- An explosion was reportedly heard in Iran's southern city of Bandar Abbas, Sabereen News reported [Details light].
- US President Trump urged European countries to close their borders and deport migrants; Trump criticised Europe for failing to support the US over Iran and suggested Washington could reconsider its support for Europe, via Truth Social.
- Iranian President Pezeshkian said US bases in the region provide no benefits and only fuel insecurity, Press TV reported.
- Two Pakistani soldiers were reportedly killed in the Wadi al-Miftah area near the Saudi-Yemeni border, IRNA reported, citing Yemeni media.
- US War Secretary Hegseth met Israeli PM Netanyahu during an unannounced visit to Israel on Monday, Axios reported.
- Yemeni forces reportedly targeted Saudi Arabia's Dammam airport with missiles and drones, temporarily suspending operations, Tasnim reported, citing Al-Masirah.
- Russian Foreign Minister met Iran's President and Supreme National Security Council Secretary in Tehran, following earlier talks with his Iranian counterpart, Iran Nuances reported.
- US President Trump said good situation with respect to Iran; negotiating with Russian President Putin on Ukraine; negotiating on Iran and with diesel with Russia; Russia has been fine on Ukraine. Ukraine's President Zelensky is not helping matters much. Time for someone else to negotiate on behalf of Ukraine.
- IRGC spokesperson said 7 major cables have passed under the Strait of Hormuz, on which all the world's internet and commercial data depends; we remind the enemy of this so that they know.
- US Official said Iran's claim that the US struck an Iranian naval base is inaccurate, reported CNN.
- Houthis target Marib city with ballistic missiles, reported Sky News Arabia.
- Iranian President Pezeshkian said Iran has no fundamental differences with regional countries and is ready to resolve existing issues through dialogue.
- Pakistani Army Chief Asim Munir arrives in Tehran today (20th Oct) to meet with Iranian officials, Al Jazeera reported.
- The operation to neutralize and destroy unexploded ordnance left over from the imposed war has begun in the north of Bandar Abbas and, according to Hormozgan officials, Nour News reported; will continue for the next two days.
- IRGC Spokesperson: In the new phase of the war, new weapons and targets will be unveiled, Fars reported.
- Houthis claim six attacks on Saudi Arabia in 48 hours; strikes include Yanbu Aramco facility, Shaybah oilfield, Riyadh and Abha airports.
- Iranian Foreign Minister Araghchi said Iran-Russia cooperation is closer than ever, with talks covering regional developments and expanding economic and nuclear cooperation, IRNA reported.
EU/UK
NOTABLE HEADLINES
- UK Chancellor Healey has reportedly ruled out raising capital gains tax in the October 28th Budget amid concerns over growth and investment, The Times reported. The Chancellor reportedly plans to increase taxes on banks, introduce targeted cost-of-living support and reduce fiscal headroom from GBP 23bln to around GBP 15bln in the October 28th Budget.
- Germany Chancellor Merz said Germany needs to overhaul social security system; No need for a fast decision on ECB positions, but a quick decision can be reached on ECB jobs if needed. Nvidia (NVDA) plans to invest "billions" in Germany.
- US State Department approved a potential sale of general infrared countermeasure systems to the Netherlands.
NOTABLE GLOBAL EQUITY HEADLINES
- OpenAI is reportedly rushing to secure investor commitments for a private funding round ahead of Anthropic's IPO, with SoftBank (9984 JT) and MGX in discussions to participate, according to sources.