
US Market Open: Iran's Foreign Ministry suggested that the country favous diplomacy, though crude benchmarks continued to move higher; GBP gains post-jobs data
Newsquawk Analysts ·
Listen
0:00--:--
- Iranian Foreign Ministry said that if there is even the slightest chance that it may be able to prevent the escalation of tensions through diplomacy, it must definitely go this route.
- US equity futures mixed, NQ under pressure as tech resumes last week's selloff.
- DXY slightly lower; GBP firmer on an upbeat jobs report, while JPY unmoved following BoJ sources.
- Fixed income benchmarks have a slight positive tilt; JGBs boosted by a strong 20-year auction.
- Energy benchmarks are firmer despite the IEA head considering a further release of emergency stocks.
- Looking ahead, highlights include US Building Permits (Sep), NBH Policy Announcement. Speakers include BoE's Greene & RBA's Hauser. Earnings from EssilorLuxottica, GE Aerospace, General Motors, Northrop Grumman, Netflix, SpaceX & United Airlines.
SNAPSHOT
EUROPEAN TRADE
EQUITIES
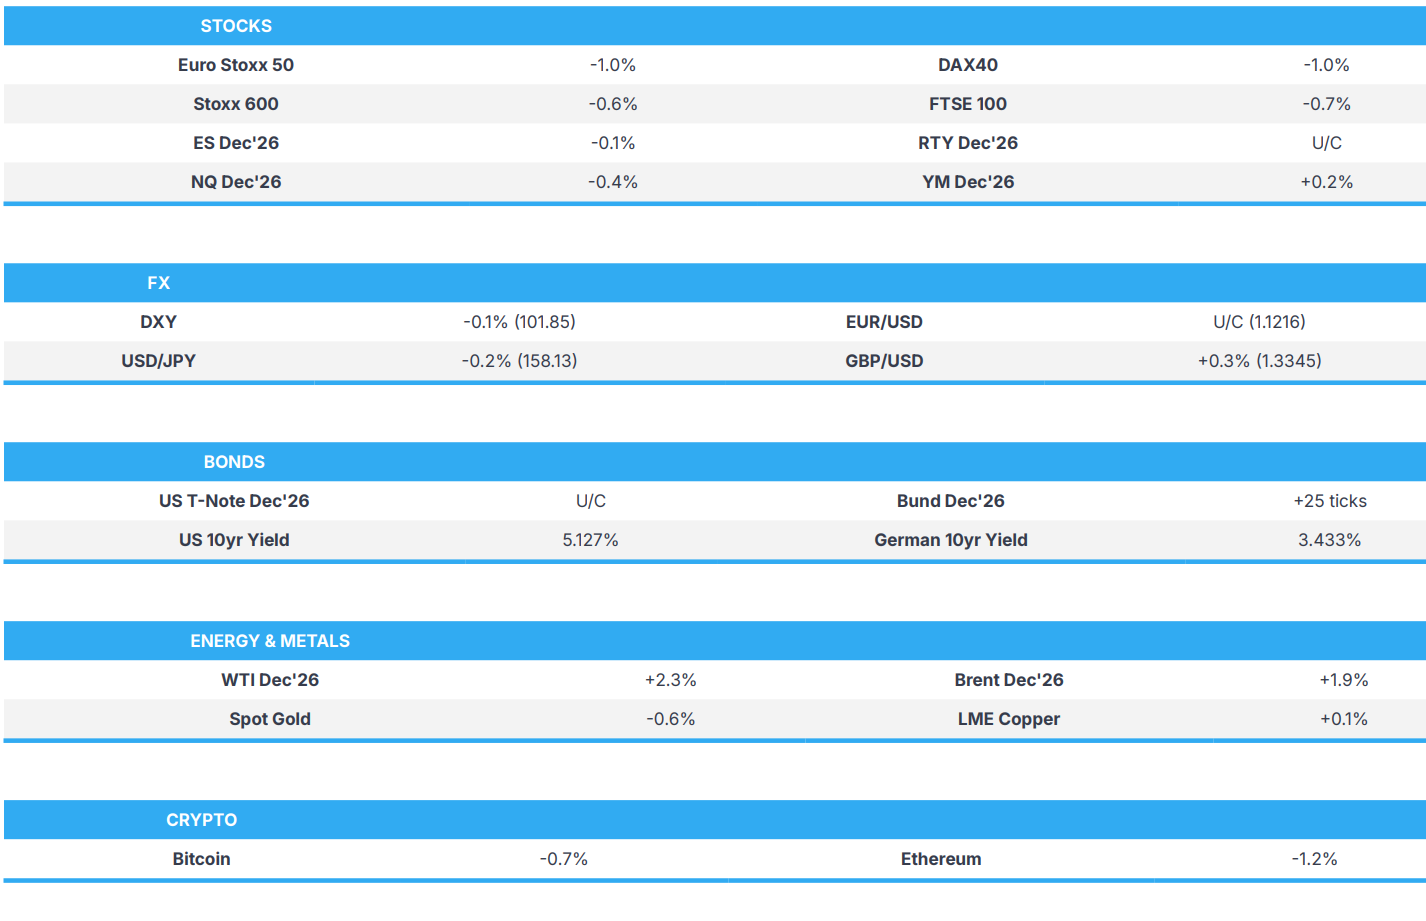
- European bourses (STOXX -0.6%) are lower again on Tuesday, not helped by the risk tone in Asian equities, while updates from several companies also disappointed. Focusing on South Korea, Elice had a poor debut, slumping as much as 30%. This can have a read-across for the tech space as Elice is a data-centre firm which provides AI cloud services as well as AI-based education and business software. To note, the IPO price was set before the recent sell-off in AI-related stocks, exacerbating the downside on debut day.
- Sectors highlight the negative bias. Health Care tops the sector pile, with Optimised Personal Care and Food, Beverages & Tobacco rounding out the top three. To the downside reside Industrials, with Tech and Basic Resources following closely behind.
- US equity futures are mixed, with the NQ underperforming as it gives back some of Monday’s gains. Plenty of earnings to keep an eye on today, which include RTX, GM, GE Aerospace and SpaceX.
- Click for the sessions European pre-market equity newsflow
- Click for the additional news
FX
- G10s are stronger against the broadly softer USD, and to varying degrees. The Kiwi outperforms, followed closely by the Loonie. The EUR is flat, and is the mild underperformer this morning.
- USD is under very mild pressure this morning, but has found some strength as it trades in a 101.74 to 101.98 range; the low of the day coincides with its 21-DMA. There is no specific driver for the pressure this morning, but perhaps as AI-concerns remain front of mind, particularly as the swap on CoreWeave CDS remains elevated beyond 1,000 points. With the data docket fairly light for the remainder of the week, and the Fed on blackout, markets will have to use geopolitical developments and/or tech earnings as a proxy for sentiment. Bar any debt-related concerns, the index should remain within familiar ranges into the FOMC next week.
- Kiwi is the mild outperformer this morning, benefiting from slightly firmer copper prices. The Loonie has been lifted in the past few days amidst a recent hawkish repricing at the BoC; as it stands, money markets assign a c. 80% chance of a hike next week (vs c. 40% last week). To remind, BoC Governor Macklem recently stated that higher energy prices are lifting the inflation outlook, signalling that the Bank stands ready to raise rates.
- The GBP benefits from a better-than-expected UK Jobs report. In brief, the Unemployment Rate fell to 4.7% vs expectations of it holding steady at 4.9%; Employment Change also jumped from the prior, and above consensus. As for the wage components, they remain benign, with little evidence of second-round effects filtering through so far. Overall, this report will provide confidence to the more hawkish members on the MPC, to deliver a rate hike in November. Following the data, Cable rose from 1.3328 to 1.3358, and currently holds at the upper end of the day’s 1.3302-1.3358 range.
- EUR is flat vs the USD, and the only G10 currency failing to benefit from the softer Dollar. Pressure that stems from the ongoing widening of the OAT-Bund spread, which has now breached its recent peak of 151bps; a move which comes amidst ongoing civil unrest in France, and now several parts of Europe. Adding to the negative sentiment is a poor German/EZ ZEW Sentiment read, which fell from the prior and by more than expected.
FIXED INCOME
- A contained start for fixed generally, USTs in a thin 105-05 to 105-12+ band, into a much busier docket than Monday, but one that is still generally awaiting events over the next few weeks; barring a significant geopolitical development, of course.
- Currently, this leaves USTs entirely within Monday’s confines, by just a tick at the low-end and 12+ at the upper-end. Yields lower across the curve, though only marginally and with no overt flattening/steepening bias currently seen.
- EGBs tracked USTs overnight, with a modest haven bid coming from the tepid APAC risk tone, but offset by energy upside, points that left the space near-enough flat in early trade. Thereafter, a hawkish UK job series pushed Bunds down by about five ticks, before this unwound and a 121.39 peak printed in the early morning.
- Specifics for the bloc thus far a little light, we mainly await updates on the fiscal front, as Politico suggests that German Chancellor Merz and French President Macron are more aligned on the need to get the next framework done by end-2026. Albeit, the immediate focus is on the weekend’s unrest, with French curfews approved more widely, though the litmus test will be the coming weekend’s planned action; and then the demonstrations unions are calling for in early-November.
- Reflecting the ongoing French political, and by extension, fiscal risk, the OAT-Bund 10yr yield spread has widened to a 151bps peak today, swiftly approaching the 152bps high from just after the draft budget was presented. Again, such widening does not bode well into Moody’s on Friday.
- Finally, Gilts opened with some modest downside, but didn’t stray too far from the 84.00 handle. Thereafter, some slight choppiness was seen in 83.85 to 84.13 confines amid a number of factors being digested at once; since, it has slipped into the red and marginally lags.
- Pressure that comes on the energy upside and hawkish jobs data, the latter being another factor in favour of a BoE hike in November, or at the very least by end-2026. Elsewhere, the discussed risk tone would have had a modest offsetting influence. While reports around the budget could be taken either way. Specifically, The Times reported that Chancellor Healey has abandoned plans to increase Capital Gains Tax, due to the likely growth hit. A point that reduces his revenue-raising avenues, and this means a lower headroom is likely to result; however, it factors well for confidence levels in domestic business.
- Germany sells EUR 0.992bln vs Exp. EUR 1bln 2.10% 2029 Green Bobl and 1.80% 2053 Green Bund.
- The UK sells GBP 4.25bln 4.875% 2036 Gilt: 3.61x (prev. 3.34x), Average Yield 5.418% (prev. 5.383%), Tail 0.2bps (prev. 0.5bps).
- Japan sells JPY 700bln 20yr JGB; b/c 5.84x (prev. 4.01x). average yield 3.7230% (prev. 3.8560%), tail 0.07 (prev. 0.15).
COMMODITIES
- Crude benchmarks have been choppy at the start of Tuesday’s European session, but ultimately reside at the top end of their daily range. WTI briefly tops USD 100/bbl (USD 98.04-100.93/bbl) while Brent holds above USD 110/bbl (USD 109.00-USD 111.75/bbl).
- Geopolitical headlines have been light thus far. Overnight, the IRGC said it downed a US MQ-9 drone over Hormuz. Elsewhere, Saudi Arabia and Houthis continue to strike each other, with reports this morning suggesting that Saudi intercepted missiles heading towards Riyadh.
- As for the path to diplomacy, Pakistan’s Army Chief has arrived in Tehran, so focus will be on any updates following these talks. Recent comments from Iranian officials have suggested that he is yet to arrive in Tehran. This morning there were some updates from the Iranian Foreign Ministry spokesman who struck a conciliatory tone, but ultimately did not spur a reaction in the crude complex. He mentioned that Iran held several contacts and consultations, adding that if there is even the slightest chance that it may be able to prevent the escalation of tensions through diplomacy, it must definitely go this route. However, sticking points in negotiations remain on the Strait of Hormuz and nuclear issues.
- Dutch TTF is back on the climb, and currently sits at the upper end of its EUR 87.60-89.80/MWh range, with the peak just above Monday’s peak of EUR 89.70/MWh.
- Precious metals continue to gradually fall, with spot gold at the lower end of its USD 4116-4147/oz range, but remains well-contained within the wider USD 4067-4228/oz band. The yellow metal will continue to be driven by yields. The next level on the US 10yr that could spur upside in the precious metal is back below the 5% level.
- 3M LME Copper briefly slipped below USD 14.3k/t, falling to a trough of USD 14.27k/t before rebounding to a current peak of USD 14.41k/t. Traders highlight the risk of tariffs as a downside risk for the red metal. The metal benefited from the surge of copper being piled in the US, in anticipation of tariffs being placed on copper imports. However, this possibility is fading somewhat, according to a trader at Ningbo.
- IEA Chief Birol said they will consider releasing more emergency stocks if needed.
- US Energy Secretary Wright said no Russian Diesel has been released yet and yet to be seen if Russia will release diesel.
- Saudi and the UAE have committed to provide 95k and 100k tonnes per month, respectively, of diesel to France. Deliveries to begin in the coming weeks.
TRADE/TARIFFS
- The UK Treasury is expected to be asked to assess the economic benefits of closer ties with the EU, including a potential customs union, single market return or full EU membership, ahead of the November 20th Brussels summit, according to the FT.
NOTABLE EUROPEAN HEADLINES
- UK Chancellor Healey has reportedly ruled out raising capital gains tax in the October 28th Budget amid concerns over growth and investment, The Times reported. The Chancellor reportedly plans to increase taxes on banks, introduce targeted cost-of-living support and reduce fiscal headroom from GBP 23bln to around GBP 15bln in the October 28th Budget.
- French President Macron and German Chancellor Merz got behind agreeing an EU budget before end-2026, Politico reported citing officials. However, a German source said no landing zones of specific numbers have been agreed.
- German Chancellor Merz said they aim to quadruple AI compute capacity by 2030 with its data centre strategy. Following this, Amazon (AMZN) announced plans to invest EUR 16bln in Germany in 2027, pledging to build more sustainable infrastructure across Germany and to strengthen water-resource management.
- US President Trump urged European countries to close their borders and deport migrants.
NOTABLE EUROPEAN DATA RECAP
- UK Unemployment Rate (Aug) 4.7% vs. Exp. 4.9% (Prev. 4.9%).
- UK Employment Change (Aug) 102K vs. Exp. 20K (Prev. 67K).
- UK Claimant Count Change (Sep) 30.3K vs. Exp. 19.4K (Prev. 7.0K).
- UK HMRC Payrolls Change (Sep) 13K (Prev. 1K).
- UK Average Earnings excl. Bonus (Aug 3MYr) 3.7% vs. Exp. 3.6% (Prev. 3.6%).
- UK Average Earnings incl. Bonus (Aug 3MYr) 3.7% vs. Exp. 3.8% (Prev. 3.9%).
- European ZEW Economic Sentiment Index (Oct) 18.5 vs. Exp. 23.6 (Prev. 25.8).
- German ZEW Economic Sentiment Index (Oct) 28.1 vs. Exp. 30 (Prev. 34.7).
- German ZEW Current Conditions (Oct) -35.9 vs. Exp. -45 (Prev. -47.1).
- German PPI (Sep MM) 1.9% vs. Exp. 0.8% (Prev. 1.1%).
- German PPI (Sep YY) 6.7% (Prev. 4.6%).
CENTRAL BANKS
- The BoJ is reportedly likely to keep rates unchanged in October, but could signal that a rate hike could come in December, according to Reuters sources. The report added that the Bank may also raise its FY27 inflation forecast slightly.
NOTABLE US HEADLINES
- US President Trump posted that American incomes have reached record highs, employment and exports are at all-time highs, and the US is now the "hottest" country in the world.
- ByteDance, Alibaba (BABA) and Tencent (0700 HK) have reportedly ordered in excess of 3mln NVIDIA (NVDA) RTX Pro 5500 workstation GPUs, with a combined value of more than USD 35bln, sources suggested.
GEOPOLITICS
MIDDLE EAST
- US President Trump criticised Europe for failing to support the US over Iran and suggested Washington could reconsider its support for Europe.
- Iran's IRGC said it intercepted and destroyed a US MQ-9 drone over the Strait of Hormuz using its new advanced air defence system.
- Iranian Foreign Ministry Spokesperson Baghaei said they have held several contacts and consultations and that if there is even the slightest chance that it may be able to prevent the escalation of tensions through diplomacy, they must definitely go this route. On talks with Russia, Baghaei said there was no discussion about nuclear negotiations with the US, and that Iran are not negotiating with the US in this regard.
- Iranian Foreign Ministry said the US' response to the proposal from Iran was incomplete and insufficient.
- Iranian President Pezeshkian said US bases in the region provide no benefits and only fuel insecurity, Press TV reported.
- Iranian Foreign Minister Araghchi said Iran-Russia cooperation is closer than ever, with talks covering regional developments and expanding economic and nuclear cooperation, IRNA reported.
- Qatari Foreign Ministry spokesperson said "We are working with Washington and Tehran in partnership with other mediating countries to end the war in the region."
- Pakistan Army Chief Munir has arrived in Tehran to meet with senior officials of Iran.
- Russian Foreign Minister met Iran's President and Supreme National Security Council Secretary in Tehran, following earlier talks with his Iranian counterpart, Iran Nuances reported.
- An explosion was reportedly heard in Iran's southern city of Bandar Abbas, Sabereen News reported.
- Yemeni forces reportedly targeted Saudi Arabia's Dammam airport with missiles and drones, temporarily suspending operations, Tasnim reported, citing Al-Masirah.
- Israeli PM Netanyahu said there are indications that Iran and its proxies want to challenge Israel before the elections.
- US War Secretary Hegseth met Israeli PM Netanyahu during an unannounced visit to Israel on Monday, Axios reported.
RUSSIA-UKRAINE
- US President Trump's envoys Kushner and Witkoff plan to travel to Norway this week for Ukraine talks and Ukraine President Zelensky is expected to join talks.
- Ukrainian President Zelensky said he talked with US Secretary of State Rubio on the topics of ballistic interceptors and Starlinks. He later said that Ukraine supports a mutual energy ceasefire.
- Ukraine's DTEK said a Russian attack struck three of its energy facilities in the Odessa region.
- The Trump administration has delayed approving transfers of Patriot interceptor missiles to Ukraine from partner countries, Washington Post reported.
CRYPTO
- Bitcoin has been choppy, briefly topping USD 82k before returning to its session low of USD 81.1k.
APAC TRADE
- APAC stocks were mostly lower despite the rebound on Wall Street, as the region failed to sustain the AI-led recovery, with chip-heavy markets in South Korea and Japan underperforming but macro newsflow rather light.
- ASX 200 declined, with gold miners pressured following Monday's pullback in the precious metal, while financials were in focus after S&P downgraded Bank of Queensland's long-term rating to BBB+ from A-, and Westpac flagged an AUD 41mln notable item related to RAMS litigation.
- Nikkei 225 was subdued as tech names failed to benefit from the AI-led rebound stateside, although the index pared some of its earlier losses of over 1%. SoftBank was in focus following reports that it is in discussions to participate in OpenAI's private funding round ahead of Anthropic's IPO.
- KOSPI was the regional laggard, extending its October rout, with Samsung Electronics and SK Hynix pressured amid reports that US big tech firms are pushing for lower memory prices by citing Chinese suppliers as alternatives.
- Hang Seng and Shanghai Comp diverged, with Hong Kong lower as it returned from Monday's Chung Yeung holiday, while the mainland was flat as Chinese LPRs were maintained, as expected.
NOTABLE ASIA-PAC HEADLINES
- Japanese Finance Minister Katayama said no decisions have been made on funding defence spending increases, but measures to secure stable funding will be considered while maintaining fiscal sustainability.
- China's NDRC said it will introduce additional policy measures as needed to keep economic activity within a reasonable range.
NOTABLE APAC DATA RECAP
- Chinese Loan Prime Rate 1Y (Oct) 3.0% vs. Exp. 3.0% (Prev. 3.0%).
- Chinese Loan Prime Rate 5Y (Oct) 3.5% vs. Exp. 3.5% (Prev. 3.5%).
- Taiwanese Export Orders (Sep YY) 62.4% (Prev. 71.4%).