
US Market Open: Crude benchmarks stronger after the IRGC warned US bases; TSLA falls post-earnings
Newsquawk Analysts ·
Listen
0:00--:--
- Iran's IRGC Navy warned that US efforts to encourage passage could result in strikes on US bases.
- Iran's Major General Rezaei said Iran has presented seven new conditions through mediators and will neither reopen the Strait of Hormuz nor resume negotiations until they are met.
- NQ underperforms, as Tesla's cut in spending plans weighs on the Tech/AI space.
- DXY modestly lower; JPY and CHF supported by haven demand while NZD lags on cooler CPI.
- Fixed income benchmarks helped by risk aversion.
- Energy benchmarks climb as Iran warns of strikes on US bases (Brent +2.9%)
- Looking ahead, highlights include US Jobless Claims (Oct/17), CBRT Policy Announcement (Oct). Supply from the US. Earnings from American Airlines, Blackstone, Valero Energy, Bloom Energy, L'Oreal.
SNAPSHOT
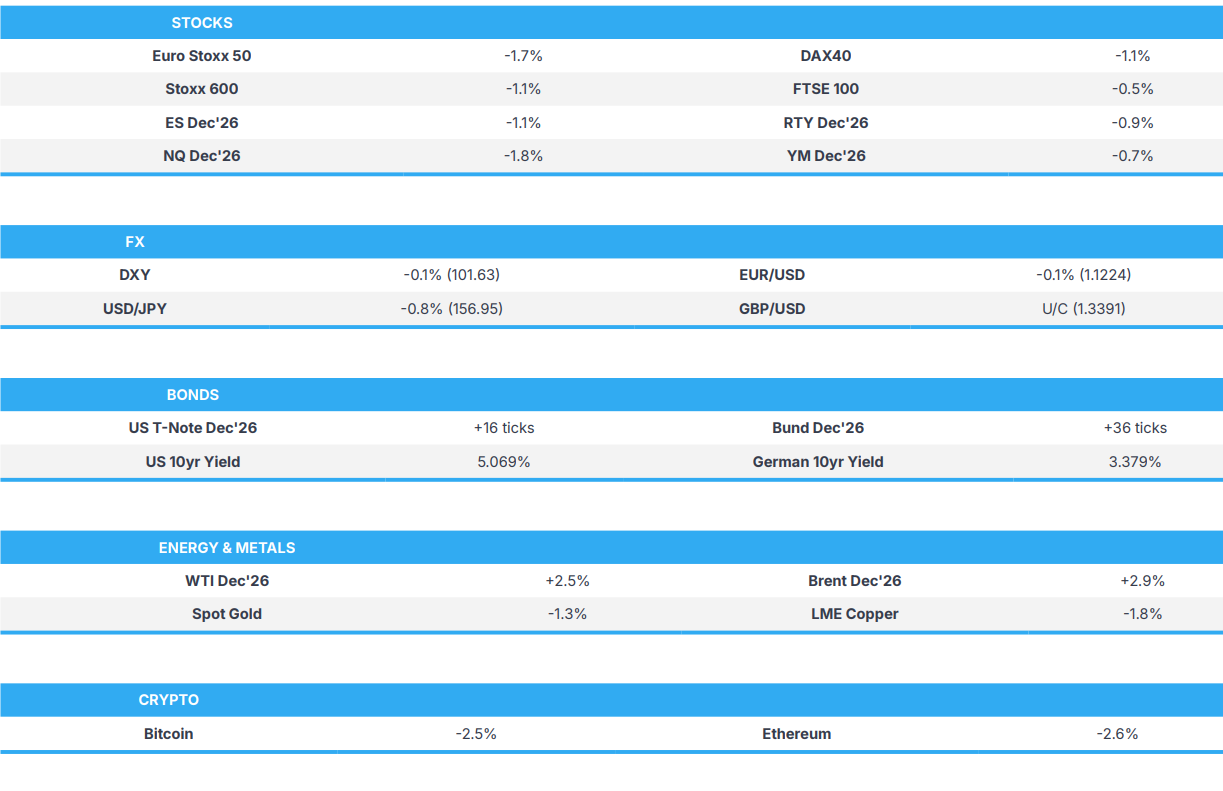
EUROPEAN TRADE
EQUITIES
- European bourses are under pressure this morning, following on from the weakness seen in Asia. In Hong Kong, the likes of Alibaba (-6.1%) and PDD (-3.6%) slipped after China’s CMRC urged e-commerce platforms to strengthen product quality controls and consumer protection.
- Sectors highlight the negative bias. Telecoms, Food, Beverages & Tobacco and Health Care are the sector gainers. The underperformer is Basic Resources, followed by Banks and Tech.
- Key earnings include: SAP -0.9%, despite Q3 metric beats and sees FY26 cloud revenue at the upper end of its guided range; Nestle +1.6%, Q3 sales beat and reaffirms its FY26 sales growth target; Roche -0.5%, despite Q3 sales topping estimates and reaffirms FY outlook; Nokia -5.3%, despite Q3 profit beating expectations and expects supply chain constraints to continue in 2027.
- US equity futures follow the broader space lower, with underperformance in the NQ, pressured by Tesla (-4.5% pre-market) after reporting slower deliveries growth. Meta (-1.2% pre-market) follows sentiment lower, despite reporting strong Q3 results, but with potential focus on the Co. being ordered to pay a USD 25bln penalty to New Mexico.
- Meta Platforms Inc (META) Q3 2026 (USD): EPS 3.83 (exp. 6.67), Revenue 64.6bln (exp. 63.31bln). Q3 includes a USD 9.89bln charge related to the teen mental health litigation agreement; excluding the charge, EPS would have been 7.40. Q4 revenue guidance 73-76bln (exp. 73.64bln); FY26 capex guidance 135-145bln (prev. 130-145bln). Announced new non-voting Class C shares, distributed one-for-one to Class A/B holders.
- Tesla (TSLA) Q3 2026 (USD): Adj. EPS 0.48 (exp. 0.45), Revenue 28.0bln (exp. 28.1bln). Gross margin 19.6% (exp. 17.8%). FCF 1.53bln (exp. -4.99bln). On the call, CEO Musk said the company is aiming to produce approximately 5mln vehicles annually by 2030, while FY capex guidance was revised to approximately USD 20bln (prev. USD 25bln).
- Click for the sessions European pre-market equity newsflow
- Click for the additional news
FX
- Snapshot: G10s are mixed against the USD. JPY is the clear outperformer, joined closely by the CHF, benefiting from haven flows. On the flip side, the Antipodeans have been hampered by the risk tone, whilst the Kiwi digests cooler-than-expected CPI.
- DXY is on the back foot this morning, pressured by lower yields, which comes despite elevated energy prices. The index currently holds at the upper end of a 101.44 to 101.73 range; price action today will likely be dictated by cross-asset relationships, given that the data docket remains light today. Some of the pressure today may also be facilitated by poor results from Tesla.
- The JPY is the outperformer this morning, benefiting from its safe haven status. USD/JPY currently holds at the bottom end of a 156.76 to 158.25 range, a move which will no doubt be welcomed by Japanese officials. Focus for geopolitics was on an IRGC warning to US bases, that they may be a target if the US continues to allow ships to pass through the Strait of Hormuz. Aside from geopolitics, the JPY is digesting reports that Japan is considering the resumption of energy subsidies. Whilst this does reduce the inflationary implications of recent energy price rises, the overarching question is how Japan intends to finance this; of course, options include a supplementary budget, which could involve bond issuance, further fuelling fiscal woes. Elsewhere in Japan, the RENGO union is reportedly seeking a 6% wage increase for 2027, an increase from the 2026 figure of 5.01%; for reference, the union had demanded 5.94% in 2026.
- The Antipodeans are the slight laggards this morning, given the subdued risk tone. The Kiwi mildly underperforms vs the Aussie following a cooler-than-expected CPI report, but still remains at elevated levels. Therefore, money markets still expect the RBNZ to hike rates at next week’s meeting; Westpac sees rates to be hiked by 25bps.
FIXED INCOME
- In brief, a haven bid is seen across most core fixed income, as the geopolitical situation escalates and yields prove somewhat resilient to the energy upside, as much of that is priced by this stage, with focus instead increasingly on the growth side of the equation.
- USTs just off a 105-19+ peak, firmer by 16 ticks at best. The docket ahead is relatively light, but the focus is firmly on geopolitics after the activity seen in APAC hours and the continued dissemination of punchy rhetoric in the European morning.
- Bunds also bid, and in-fitting with USTs for the most part. At a 121.90 high, firmer by 50 ticks. As above, specifics are relatively light and the focus is firmly on geopolitical developments for core counterparts.
- In brief, while the focus for core debt is increasingly on the growth implications of the ongoing Middle East situation, this is not to a degree that is likely to dissuade policymakers from tightening in the weeks ahead, with the BoE for instance expected to start its tightening cycle; though, it is expected to be brief.
- Continuing with the UK, Gilts opened with modest gains, given the above haven allure factoring initially, before then being briefly unwound/offset by energy’s influence. However, Gilts broadly conform to peers, with gains of around 15 ticks currently, some 10 off the 84.73 peak.
- More pertinently, those under significant fiscal scrutiny are seeing a selloff as the growth-hit and inflationary angle combine to further knock the fiscal backdrop. A point that is particularly evident in France, with OATs down by over a point at most, lifting the 10yr yield to a 5.14% high, and widening the OAT-Bund spread to 1.73%, the highest since January 2011.
- The UK sells GBP 1bln 0.125% 2031 I/L Gilt: b/c 3.99x (prev. 4.26x), real yield 1.141% (prev. 0.933%).
COMMODITIES
- Crude benchmarks have climbed throughout the APAC session and continue as Europe steps in. Iran’s IRGC Navy said four vessels transferring oil cargoes were struck in the Persian Gulf, while three other vessels hit sea mines yesterday west of the Strait of Hormuz, warning that US efforts to encourage passage could result in strikes on US bases. With repeated airing of these comments, it has continued to support the energy complex. WTI briefly topped USD 100/bbl, but currently holds at the upper end of its USD 97.72-100.09/bbl range, while Brent trades in a USD 109.81-112.68/bbl range. All being said, the crude complex remains contained within Tuesday’s broad range.
- Elsewhere, the NYT reported that the US and Israeli militaries have developed plans for renewed strikes on Iran after the US midterm elections, targeting energy infrastructure, nuclear facilities and missile and drone arsenals, while Israeli press cited US official comments that there has apparently been a change in the American position in favour of a pre-emptive strike on Iran.
- Spot gold has come under pressure in the European morning, as it resides at the lower end of its USD 4067-4146/oz range. Zooming out to the range formed over the past month, the yellow metal sits at the bottom of that range (USD 4066-4228/oz). The precious metal has not been favoured by usual risk-off flows or a weaker dollar, but instead found headwinds from escalating Middle East hostilities, which have raised inflation risks ahead of the Fed decision next week.
- 3M LME Copper slid overnight and currently holds at the bottom end of its USD 14.09k-14.37k/t range. The red metal is tracking the losses in the equity space, over continued worries of the AI trade. Copper has benefited recently due to its use in data centres and power infrastructure.
- US waived Russian diesel tax record requirements for buyers.
- Russia's Novatek is to redistribute its LNG globally when the ban on its imports into Europe comes into effect, RIA reported.
- Iraq is looking to charter tankers to ship fuel oil outside of the Strait of Hormuz.
- Saudi Aramco CEO expects oil demand to increase by 3mln BPD once the Middle East conflict ends. The CEO added that oil could have been higher during the crisis; one factor that offset it was the east-west pipeline.
- Libya's NOC said unidentified people have entered the crude-receiving station near the Zawiya refinery (120k BPD) and closed the pipeline valves.
TRADE/TARIFFS
- China's MOFCOM said it is to improve its trade friction response mechanism.
NOTABLE EUROPEAN DATA RECAP
- French Business Confidence (Oct) 105 vs. Exp. 101 (Prev. 101).
- French Business Climate Indicator (Oct) 98 vs. Exp. 96 (Prev. 96).
- UK CBI Industrial Trends Orders (Oct) -32 vs. Exp. -20 (Prev. -9).
CENTRAL BANKS
- BoK left its rate unchanged at 3.0% as expected. BoK said today's rate decision was unanimous, while the timing and pace of further rate hikes will depend on inflation, economic conditions and financial stability. It is essential to assess domestic and external risks and the impact of the previous two rate hikes. Expects inflation to remain above its target for an extended period. Stock price volatility has increased amid concerns over slowing semiconductor sector profitability and investment. Financial imbalances related to the housing market and household debt require continued attention. Expects exports and investment to sustain strong growth. SNB Minutes (Sept): The rise in inflation since the beginning of the year has been largely attributable to the increase in oil product prices, but there are still no signs of second-round effects, and core inflation has risen only slightly. At the same time, medium-term inflationary pressure is only slightly higher, and the new conditional inflation forecast shows that inflation is within the range consistent with price stability over the entire forecast horizon. On FX, the Minutes state that the SNB is also willing to be active in the foreign exchange market as necessary to ensure appropriate monetary conditions, but that the increased willingness to intervene is no longer necessary in the current environment.
NOTABLE US HEADLINES
- BofA Total Card Spending (week to October 17th) +4.9% Y/Y (prev. +5.1%); lower-income spending growth has consistently outpaced higher-income spending growth over the past several weeks.
- Some US banks are reportedly detecting unauthorised AI agents operating within accounts, Axios reported citing sources. The report added that the banks affected include Morgan Stanley (MS), Bank of America (BAC), JPMorgan (JPM), Wells Fargo (WFC).
GEOPOLITICS
MIDDLE EAST
- Iran's IRGC Navy said four vessels transferring oil cargoes were struck in the Persian Gulf, while three other vessels hit sea mines yesterday west of the Strait of Hormuz, warning that US efforts to encourage passage could result in strikes on US bases. Furthermore, Fars reported similar commentary by the IRGC Navy, stating that confrontation could extend to US bases if Washington continues “encouraging” vessels to use an “illegal” route in the Strait of Hormuz.
- Iran's Major General Rezaei said if diplomacy can create this understanding, Iran prefers diplomacy but warned that continuing the current situation will have strategic consequences, including that energy markets will not calm down for the next three years.
- Iran's Major General Rezaei said Iran has presented seven new conditions through mediators and will neither reopen the Strait of Hormuz nor resume negotiations until they are met.
- Israeli PM Netanyahu said 90% of the mission has been accomplished in Iran and that striking Iranian nuclear facilities is not enough as long as the regime remains in power, Channel 12 reported. Additionally, Israeli PM Netanyahu said he will inform US President Trump of Israel's plans regarding Iran but will not seek his approval for any strikes, according to Al Arabiya.
- US and Israeli militaries have reportedly developed plans for renewed strikes on Iran after the US midterm elections, targeting energy infrastructure, nuclear facilities and missile and drone arsenals, NYT reported, citing sources.
- US military is reducing troop presence at bases across the Middle East, while the State Department is ordering further staff reductions at diplomatic posts amid regional threats and potential US military action against Iran, NBC News reported.
- "The likelihood of a renewed war with Iran is increasing", Israeli Walla reported citing a security official.
- Explosions were reportedly heard in Iran's port city of Sirik, with claims that US forces struck an anti-ship missile launcher targeting vessels in the Strait of Hormuz, Israel's Channel 12 reported.
- Saudi Civil Aviation said King Fahd Airport in Dammam was attacked on Wednesday evening, Al Arabiya reported.
- Saudi Arabia's Eastern Province was reportedly targeted by four drones, Naya for Iraq reported.
- An Aramco facility in Saudi Arabia was on fire, Sabereen News reported.
- Saudi Aramco has reportedly instructed staff to evacuate its Dhahran headquarters and work from home, according to sources.
RUSSIA-UKRAINE
- Russian Kremlin said there are no current plans for a conversation between President Putin and US President Trump, but it could be organised quickly if required.
- A drone struck energy infrastructure in Ukraine's Poltava region near Kremenchuk, according to a local official.
CRYPTO
- Bitcoin slips below USD 82k, from an earlier peak of USD 84.3k as the downside coincides with the renewed pressure on risk assets.
APAC TRADE
- APAC stocks were pressured and extended on losses throughout the session despite the positive lead from Wall Street, as AI and semiconductor names were sold after Tesla cut capex guidance, Lam Research fell after-hours, and Meta's results stoked concerns over the financial strain of heavy AI investment. Middle East tensions also remained in focus, with the US preparing ordered departures at embassies across the Gulf and reports of renewed attacks on Saudi Arabia.
- ASX 200 was lower, with energy and retail stocks leading the declines as Nick Scali slumped after its profit warning and weighed on fellow retailers, although the index pared some of its earlier losses.
- Nikkei 225 extended on losses, with AI and semiconductor names such as Tokyo Electron, SoftBank Group, Ibiden and Fujikura pressured.
- KOSPI underperformed as concerns over investment in the AI value chain sparked a selloff in chip stocks, with Samsung Electronics and SK Hynix both pressured, while Samsung Electro-Mechanics reversed the opening gains it saw on its NVIDIA tie-up. The BoK held rates unanimously, as expected, while Governor Shin said the recent stock market correction weighs on consumption.
- Hang Seng led the declines in the region with Lenovo and Hua Hong Semiconductor each down around 7% and CATL extending its losing streak to a seventh day, while the Shanghai Comp declined amid uncertainty over the Middle East, with semiconductor names sold.
NOTABLE ASIA-PAC HEADLINES
- BoJ's October lending survey: Corporate loan demand DI rose to +3 (prev. -1), led by small firms (+5), while banks' lending stance DI for large firms remained unchanged at +3 and corporate loan margins continued to narrow.
- Japan's RENGO set 2027 wage negotiation target centred on a 6% pay increase, while maintaining a minimum benchmark of at least 5%, aiming to sustain wage growth momentum following three consecutive years of average pay rises exceeding 5%.
- Japan is reportedly considering broadening the definition of defence-related spending to include AI, satellites, R&D and infrastructure such as ports and railways, amid US pressure to increase defence outlays and domestic fiscal constraints, according to sources.
NOTABLE APAC DATA RECAP
- New Zealand CPI (Q3 QQ) 0.7% vs. Exp. 0.8% (Prev. 1.5%); Y/Y 3.7% vs. Exp. 3.8% (Prev. 4.1%).
- Japanese Stock Investment by Foreigners (Oct/17) -66.5B (Prev. 3545.5B).
- Japanese Foreign Bond Investment (Oct/17) -161.6B (Prev. -339.9B).