
US Market Open: Iran targeted an air base in Bahrain in its first direct strike on the Gulf state in weeks; DXY modestly firmer awaiting Warsh
Newsquawk Analysts ·
Listen
0:00--:--
- Iran targeted an air base in Bahrain in its first direct strike on the Gulf state in weeks, while several more tankers reportedly hit mines in and around the Strait of Hormuz.
- Ukrainian President Zelensky said US envoys asked if Ukraine would give up the Donbas in exchange for NATO membership, adding he would put any formal offer to the Ukrainian public.
- The FT reported that Nvidia (NVDA) co-founder Huang is considering returning as CEO, while US Treasury Secretary Bessent said the Co. needs a 'shake-up' with an external CEO.
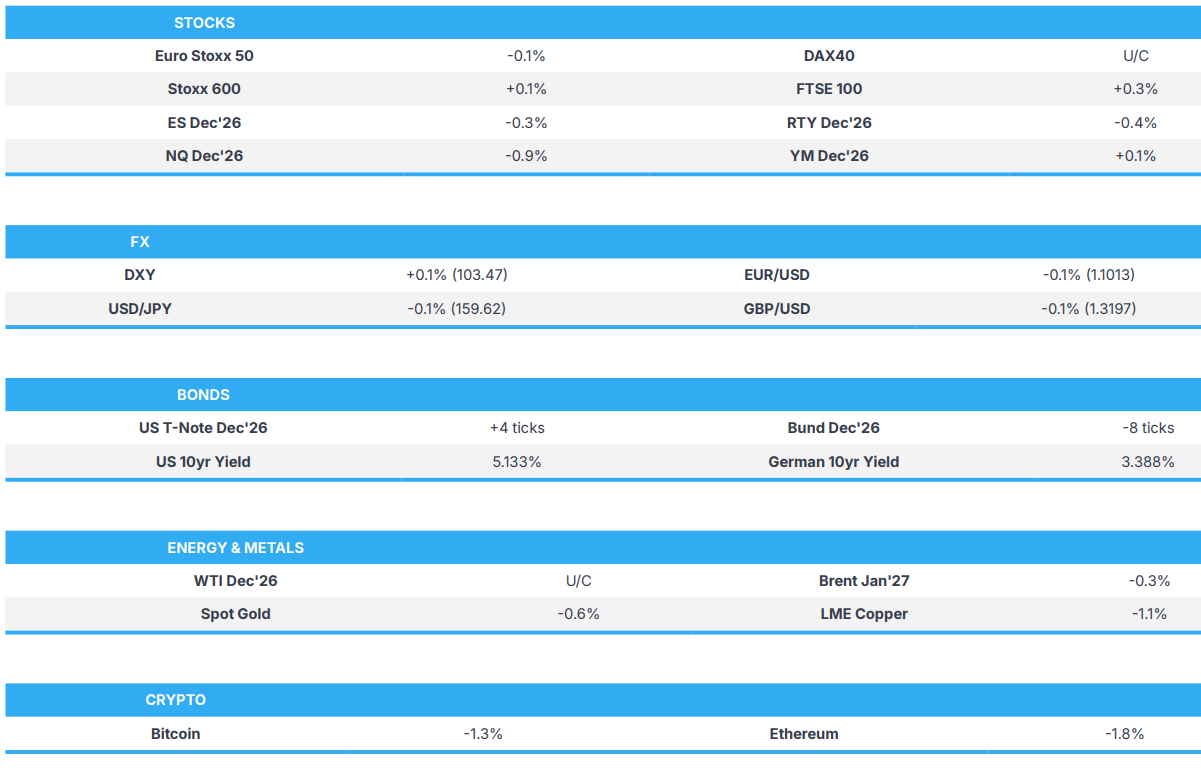
- US equity futures are mixed, with the NQ underperforming as chip stocks resume their selloff.
- DXY is modestly higher; CHF and AUD underperform.
- Energy benchmarks are rangebound; copper under pressure following weak Chinese activity data.
- Looking ahead, highlights include Canadian Inflation (Oct), ASEAN Summit (16-18 Nov). Speakers include Fed Chair Warsh & Williams, UK PM Burnham.
SNAPSHOT
EUROPEAN TRADE
EQUITIES
- European bourses (Stoxx 600 +0.1%) are broadly higher to start the week, as they continue to act as the anti-AI trade. Further boosting European sentiment is an update from Morgan Stanley, forecasting a 15% gain by the end of 2027, citing continued diversification flows and earnings growth.
- The sentiment was not as positive overnight in Asia, with the Taiwanese and South Korean benchmarks under pressure after Friday's downside in US chip stocks. Uncertainty over Nvidia's leadership remains, with the FT reporting over the weekend that ousted CEO Huang discussed the possibility of returning to the tech behemoth.
- Returning to Europe, sectors have a slight positive bias. Health Care tops the sector pile, with Optimised Personal Care and Telecoms rounding out the sector gainers. Basic Resources leads the downside, given weakness in copper following disappointing Chinese activity data. Tech and Utilities complete the sector laggards.
- US equity futures are mixed with a negative bias, with the NQ the underperformer. Focus this week will be on Nvidia earnings (Tuesday AMC). Goldman expects Nvidia to report solid Q3 results and guide Q4 above consensus, helped by better-than-expected margins. Its EPS estimates for both quarters are 6% above the Street (Q3: USD 2.57 vs USD 2.42, Q4: USD 2.88 vs USD 2.73).
- Click for the session's European pre-market equity newsflow
- Click for the additional news
FX
- Snapshot: G10s are mixed against the USD. JPY leads, followed closely by the GBP, whilst the Aussie is the laggard. Focus remains on the EUR, with the single currency approaching 1.10 to the downside.
- DXY is slightly firmer and trades within a narrow 103.33-103.53 range, currently holding above the peak from last week (103.43). To remind, the recent USD strength came after hawkish Fed's Waller comments and a hotter-than-expected US CPI report; the PPI metrics thereafter tempered some of the hawkish bets, given the implications for the PCE report due later this month. Hawkish commentary from a few speakers over the weekend has kept the index elevated.
- Tier-1 data is lacking for the start of the week, so attention for the time being will be on Fed speak. Chair Warsh is on the docket today, but is set to speak on productivity and the labour force; and given that he typically avoids giving forward guidance, markets won’t be expecting a lot from him. Nonetheless, the risk he surprises markets remains.
- JPY holds slightly in the green this morning, amidst growing expectations of intervention and slight haven demand. USD/JPY holds within a 159.35-159.89 range. Overnight, Japan’s Q3 metrics were poor with the annualised figure contracting 0.1% vs expectations of +0.3%. However, there are some caveats to this report, namely poor weather and the Kyushu earthquake which led to the shuttering of some factories. MUFG opines that “we don’t expect weaker growth in Q3 that was reinforced by temporary factors to derail the BoJ’s plans for faster quarterly rate hikes”.
- The Aussie is the underperformer this morning, due to the poor risk tone overnight and following the disappointing Chinese activity data. In brief, Industrial Production missed expectations, whilst Retail Sales was also poor. Despite the poor metrics, a near-term rate cut is unlikely, with the PBoC preferring targeted stimulus instead.
FIXED INCOME
- A contained start to the week for fixed income, with USTs firmer by a handful of ticks in 105-04+ to 105-10+ parameters. The US specific docket for today features notable Fed speak, highlighted by Williams and then Warsh; both of which will be scrutinised for insight into the post-CPI/PPI and Waller discourse around December, as CME implies a modest chance of a 50bps move.
- Bunds broadly in-fitting. Specifics light, awaiting updates from the UK (see below), but focus more so on the geopolitical/energy front and as we await updates stateside with several key speakers due. Currently, Bunds are in a 121.81 to 122.05 band, and essentially flat within that.
- Gilts modestly underperform, lower by about 20 ticks and at an 84.80 low. Pressure is a function of anticipation into PM Burnham’s EU speech this evening, and as we await the Milburn review tomorrow. Points which could both see Labour rebellion against any subsequent policy decisions, and by extension potentially bring into question the viability of another Labour government.
COMMODITIES
- Crude benchmarks are choppy and little changed, having briefly slipped beneath Friday's troughs before recovering, as fresh tanker incidents around the Strait of Hormuz and Iran's strike on Bahrain were offset by reports that the US is not considering imminent airstrikes against Iran (see below for a recap of geopolitics). WTI Dec'26 trades within a USD 87.59-89.49/bbl range (vs Friday's USD 87.80-89.64/bbl range), briefly dipping beneath its 100 and 200 DMAs at USD 87.85/bbl and USD 87.64/bbl, while Brent Jan'27 moves within USD 94.32-96.77/bbl (vs Friday's USD 95.06-97.13/bbl range). Elsewhere, Goldman Sachs expects Brent to fall to USD 78/bbl by end-2027 as a surplus returns, although it pointed to near-term upside risk.
- Dutch TTF is lower within a EUR 86.65-91.28/MWh range, having slid as much as 4.7% at the start of the session before paring, as traders weigh milder weather forecasts across Europe and record US LNG exports against persistent concerns over the continent's thin winter inventories.
- Spot gold is softer within a USD 3,832.46-3,901.37/oz range (vs Friday's USD 3,867.67-3,923.09/oz range), with early upside reversed after the yellow metal was rejected at the USD 3,900/oz level, while hawkish weekend Fed rhetoric from Jefferson, Collins and Schmid could be weighing. The yellow metal remains well beneath its 21DMA at USD 4,017/oz. Spot silver underperforms within a USD 47.15-49.07/oz range (vs Friday's USD 48.49-50.79/oz range).
- 3M LME copper is softer within a USD 13,205.45-13,346.00/t range, pressured by the mostly negative risk tone in Asia and disappointing Chinese activity data, in which Industrial Production (4.8% vs exp. 5.3%), Retail Sales (0.4% vs exp. 0.8%) and Fixed Asset Investment (-8.1% vs exp. -7.0%) all missed expectations.
- In geopolitics, Iran targeted an air base in Bahrain in its first direct strike on the Gulf state in several weeks, while the IRGC reported explosions after two oil tankers hit mines in the Strait of Hormuz and warned oil firms that the southern Hormuz route is mined. Furthermore, UKMTO said a tanker was struck by an unidentified projectile while exiting the Strait at 05:58GMT, triggering an engine-room fire, with no casualties reported. ILNA reported that the US plans to escalate economic and military pressure on Iran to secure an initial Strait of Hormuz agreement.
TRADE/TARIFFS
- US and allies including Japan, Australia, Israel and the UK have agreed to identify critical AI technologies and supply chains requiring greater protection from China, according to FT. It was also reported that the Trump administration is to name NVIDIA (NVDA) among AI ‘National Champions’ in a new programme that seeks to help US AI firms compete for business overseas, according to WSJ.
- White House said US President Trump is to sign a trade deal with Thailand and will meet with Quad leaders in Manila on Tuesday, ahead of the APEC leaders meeting on Thursday in Shenzhen.
- Canadian PM Carney and Brazil's President Lula signalled closer ties on Sunday, announcing funding to protect the world's tropical forests and plans for reciprocal visits. The two leaders met on the sidelines of the Association of Southeast Asian Nations summit in Manila.
NOTABLE EUROPEAN HEADLINES
- UK PM Burnham sought to play down his own comments about rejoining the EU, saying that no one is talking about rejoining, according to Bloomberg. However, a separate report noted that PM Burnham vows to reopen the Brexit debate as he paves the way for a UK-EU ‘reset’ deal and will tell a City of London audience that he is prepared for a national discussion regarding a longer-term accord with Europe, according to FT.
- UK government said it would expand and accelerate its job guarantee programme for young people, ahead of the publication of a long-awaited review into the causes of rising youth inactivity.
- S&P affirmed Italy at BBB+; outlook positive.
NOTABLE EUROPEAN DATA RECAP
- Swiss Prelim GDP Sport Adjusted (Q3) +0.2% vs. Exp. -0.1%.
- European Industrial Production (Sep MM) 0.2% vs. Exp. 0.3% (Prev. -0.5%).
- European Industrial Production (Sep YY) -1.5% vs. Exp. -0.2% (Prev. -1.1%).
- UK Rightmove House Prices MM (Nov) -1.8% (Prev. 1.0%).
- UK Rightmove House Prices YY (Nov) -0.2% (Prev. -0.1%).
CENTRAL BANKS
- Fed's Jefferson (voter) said inflation had become the most important measure for policymakers as they considered further interest-rate increases, as well as noted that recent economic activity and labour market conditions had been solid, while price pressures remained persistent. Furthermore, he added that October price data was consistent with inflation running well above target.
- Fed's Collins (2028 voter) said a gradual path of interest-rate increases would be appropriate to lower inflation, but added that she is open-minded, while she sees the price pressures broadening and stated that inflation has been elevated for a long time.
- Fed's Schmid (2028 voter) said inflation is running too hot, and the Fed has some work to do on inflation, while he added that inflation is moving in the wrong direction and is uncomfortably above the 2% target. Schmid stated that he would push back on the idea that the Fed's inflation objective requires a reaction from any particular set of prices, such as prices for AI-related tech goods. Furthermore, he said it is not the Fed's role to affect the price of any one good or service and that the Fed, through its influence on demand, has the tools and responsibility to tackle inflation.
- BoJ Board Member Takata said price increases are now more likely to generate second‑round effects, and given that some FX market participants have recently focused on both nominal and real interest rate differentials, it is important to monitor price developments transmitted through exchange rates, while he added that such developments are among the reasons why further interest rate hikes are currently necessary. Takata said the BoJ should avoid raising rates at a predetermined pace or magnitude, and instead should respond flexibly and based on data to Japan's economic and price conditions. Furthermore, he said Japan's policy interest rate has only recently moved closer to the neutral range and that the BoJ must bring its policy rate sufficiently close to neutral to respond swiftly to potential second-round inflationary effects.
- ECB's Simkus told Econostream that he sees a December rate hike as his baseline scenario, with further tightening possible in 2027 depending on inflation developments and policy transmission. Simkus noted emerging second-round inflation effects in consumer expectations and corporate pricing plans, while inflation forecasts for 2027 and potentially 2028 could be revised higher. He said a December hike would leave monetary policy in restrictive territory.
- ECB's Vujcic warned that AI investment, sovereign debt risks and vulnerabilities in the non-bank financial sector could exacerbate financial instability. He noted that Eurozone growth remains resilient despite losing momentum in Q3, while higher energy prices pose upside risks to inflation and weaker confidence and rising borrowing costs could weigh on economic growth. In later comments, Vujcic said pricing of another rate hike next year does not seem unreasonable from where we stand at the moment, but there is much to happen between now and then.
- BoE's Chief Economist Pill stated he expects that further rate hikes will be needed to combat inflation in 2027 and that they will do what is necessary to get inflation back to 2% over time, while he is worried about the inflationary impact being magnified by second-round effects, according to FT.
- BoE's Greene said it was better to act proactively now to bring inflation under control than to take a more cautious approach and risk significant second-round effects, while she stated that "When you have no idea where inflation is going, when you're facing uncertainty, I think you need to adopt an attitude of how can I screw this up the least?"
NOTABLE US HEADLINES
- US air travel disruptions extended into a third day on Sunday, with more than 5,200 flights affected, including over 1,600 cancellations and around 3,600 delays, according to FlightAware. US Transportation Secretary Duffy said services were gradually resuming, although a full recovery may not be achieved until Monday, while the disruption followed a router replacement at an FAA facility in Arkansas, which reportedly caused a recently installed router in Texas to transmit excessive data and overwhelm other network routers.
- NVIDIA (NVDA) co-founder Jensen Huang is reportedly considering returning as NVIDIA's CEO, with allies in Silicon Valley pressuring the Co.'s board to reinstate him, according to FT. In relevant news, US Treasury Secretary Bessent said NVIDIA needs a 'shake-up' with an external CEO and stated that there needs to be an assessment of the Co.'s compliance with US export controls.
- Fed Financial Stability Report stated that asset valuation pressures continued to be elevated. Measures of equity valuations have remained high, partly driven by market enthusiasm for super intelligence. The report added that AI is the most-cited risk to the financial system, flagged as a salient risk by 87% of survey respondents.
GEOPOLITICS
MIDDLE EAST
- US Homeland Security Secretary Mullin said the US is fully prepared to counter Iranian assassination threats targeting President Trump and his cabinet, while he stressed that authorities take all threats seriously and remain focused on protecting Trump, his family and the wider public.
- US Air Force responded to reports of suspicious drone activity at a base in eastern England on Friday, which was the latest in a series of security incidents at UK facilities used by the US military. The suspected unauthorised drone activity occurred at RAF Lakenheath in Suffolk, although no personnel, aircraft or infrastructure were affected.
- USS Roosevelt arrived in the CENTCOM region, bringing the total to three carrier strike groups deployed to CENTCOM's area of responsibility, according to Axios's Ravid.
- US is reportedly not considering imminent airstrikes against Iran despite pressure from Israel, according to sources cited by Israeli i24News, while Mossad chief Gofman briefed senior US officials on Tehran's recent military build-up and sources noted that the final decision lies with President Trump, with military action remaining a possibility, although not in the immediate term.
- The US reportedly plans to intensify economic and military pressure on Iran to secure an initial agreement on reopening the Strait of Hormuz, including tighter financial sanctions, restrictions on Iranian trade and oil supply routes, and potential military action against certain supply routes. Washington is seeking a phased reopening of the Strait and gradual easing of blockade restrictions, with broader negotiations on nuclear issues, sanctions and frozen assets to follow, according to ILNA citing Eram News and diplomatic sources.
- Iran targeted an air base in Bahrain in the first direct strike on the Gulf state in several weeks, while it reiterated that a route towards ending the conflict with the US remained open. IRGC said on Sunday it had launched six drones at the Riffa helicopter base in response to what it called "blatant aggression of the US military" and claimed the drones had achieved "successful impact", although Bahrain's military said it had intercepted several Iranian aerial attacks and destroyed the projectiles.
- Iran said early on Sunday that five tankers hit mines in the Strait of Hormuz over the past 48 hours, and Iran's Navy announced late on Sunday that another oil tanker caught fire after hitting a naval mine east of the Strait of Hormuz. IRGC also reported explosions on Monday after two oil tankers hit mines in the Strait of Hormuz, while it warned oil firms that the southern Hormuz route is mined and that trusting the lies of US military officials and cooperating with them will make vessels a prey to fire. Following this, UKMTO reported a tanker was struck by an unidentified projectile while exiting the Strait of Hormuz at 05:58GMT, triggering an engine-room fire; no casualties reported.
- Iran's Foreign Minister Araghchi said Tehran is seeking friendly ties and has no inherent regional disputes, adding neighbouring states should not enable attacks and that defensive actions target only the aggressors' military sites.
- Iranian Deputy Foreign Minister Gharibabadi suggested the IAEA's request to inspect damaged Iranian nuclear facilities could be aimed at evaluating the effectiveness of US strikes, while he added that Iran would not grant inspectors access until its conditions are fulfilled and the war has permanently ended. Gharibabadi stated that the US response to Tehran's conditions lacks binding commitments, with delays in meeting certain demands diminishing the prospects of a deal, as well as cautioned that Washington could be using talks to buy time and prepare for a potential attack. Furthermore, he insisted on guarantees that all of Iran's conditions will be fulfilled and stated that Iran is seeking to create a joint regional security mechanism without the presence of foreign powers.
- Iran's Foreign Ministry spokesman Baghaei said Iran will not wait on others to safeguard national security and interests, and will rely on its own capabilities and take the most appropriate measures to protect them, while he added that Iran's use of diplomacy does not mean it expects or relies on the other side, and reiterated that any attack will be responded to. Baghaei also commented that at this stage, Iran rules out suspending uranium enrichment activities or reducing enrichment levels. Furthermore, Baghaei said that Germany, as Israel's second-largest arms supplier, should share responsibility for Israel's crimes, while he rejected French claims that Iran was responsible for a recent cyberattack on refrigeration systems at French supermarkets as baseless and stated that European states have a habit of making accusations without providing evidence.
- Saudi-led coalition said it had intercepted missiles headed towards Riyadh and drones over the Eastern Province on Sunday, while Houthi militants claimed to have targeted pumping stations 5 and 6 along the east-west oil pipeline in Saudi Arabia's Riyadh region using two drones, adding that the operation successfully met its objectives.
- Saudi forces conducted airstrikes on areas in Taiz and Lahij, Yemen, while sources reported Saudi airstrikes targeted Houthis at Hodeidah airport and a naval base, according to Sky News Arabia.
- Yemeni government forces pulled out of an area close to the Bab el-Mandeb Strait, leaving the Houthis in control.
- Australia, Canada, Italy and the UK issued a joint statement expressing concern over the dire humanitarian conditions in Gaza and called on Israel to end delays and permit the immediate, unrestricted delivery of aid throughout the territory.
- Maersk (MAERSKB DC) announced AE1, AE2 and AE3 Gemini services will now sail through the Trans-Suez route instead of via the Cape of Good Hope.
RUSSIA-UKRAINE
- US envoy Kushner said the Trump administration wanted to see direct talks between Moscow and US allies in Europe, while Kushner also commented that both Russia and Ukraine understand that practical compromises will be needed to end the war.
- Ukrainian President Zelensky said US peace envoys had asked whether Ukraine would be willing to give up the Donbas region in the nation's east to Russia in exchange for NATO membership, signalling a potential shift in Washington's negotiating approach. Zelensky said that if the US and other NATO partners formally confirmed such an offer, he would put the decision to the Ukrainian public, stressing that he could not make the decision alone and that concrete details had yet to be provided. Furthermore, Zelensky said that Russia is unwilling to agree to an energy ceasefire.
- Ukrainian President Zelensky claimed that Russian casualties, including killed and wounded, topped 50,000 in October, while he added that Ukraine has disabled over 55% of Russian oil refining capacity to date.
- Ukraine claimed a strike on a major crude-pipeline hub in Russia's Samara region on Friday, while it also said that missiles hit a petrochemical plant and a refinery in Russia's Tatarstan and defence facilities in Bryansk.
- Russian forces targeted a Naftogaz Group facility in central Ukraine on Saturday, as attacks on energy infrastructure continued, while Russia struck a cargo vessel and infrastructure at Ukraine's Chornomorsk port.
- Russian Foreign Minister Lavrov said any agreement to resolve the Ukraine conflict would be unworkable if Moscow's interests were disregarded, while he questioned the EU's potential role in peace talks and reiterated that Russia's position remains unchanged, with any settlement required to fulfil the objectives of its special military operation, in response to European Commission President von der Leyen's call for a ceasefire as a prerequisite for negotiations.
- Estonia is to shut its border crossings with Russia from December 1st following a suspected sabotage attack on a drone maker in the Baltic state over the weekend, which authorities claimed was ordered by Russia’s GRU military intelligence service, while a Russian Foreign Ministry spokesperson said it would be another bout of 'Russophobia' if Estonia intends to close its border.
- French Foreign Minister Barrot said the EU will add the St Petersburg oil terminal to its sanctions list.
- EU is to suggest a EUR 45bln Ukraine loan borrowed against the bloc's budget, according to FT.
OTHER
- US President Trump will hold a trilateral summit with Chinese President Xi and Russian President Putin on Thursday on the sidelines of the annual APEC conference, reports NYP citing sources. The discussion is expected to focus on developing a nuclear arms control pact. This was later confirmed by China. To add, China's Foreign Ministry said the upcoming meeting between Chinese, Russian and US presidents will aim to strengthen communication, manage differences and stabilise the interests of the three nations.
CRYPTO
- Bitcoin extended the selloff over the weekend, reaching a low of USD 62.03k on Sunday. Since then, the cryptocoin has consolidated in a USD 64.11k-65.36k range. Focus turns to the USD 60k handle, with a large concentration of put open interest at the key round mark, according to Deribit.
APAC TRADE
- APAC stocks began the week on the back foot with most major indices in the red as participants digested disappointing data releases and await this week's key events, including NVIDIA earnings on Tuesday and the Trump-Xi-Putin trilateral meeting on the sidelines of the APEC summit in Shenzhen on Thursday.
- ASX 200 trickled lower but with trade confined within tight parameters as the weakness in mining, materials and resources offset the gains in real estate, tech and telecoms.
- Nikkei 225 wiped out initial gains and fell beneath the 60,000 level as tech stocks led the declines, and with sentiment not helped by the disappointing preliminary GDP data for Q3, which showed a surprise annualised contraction of 0.1%.
- KOSPI underperformed with the index pressured by losses in its tech heavyweights.
- Hang Seng and Shanghai Comp were mixed, with the mainland pressured following disappointing Industrial Production and Retail Sales data, while lending figures released last Friday showed a contraction in New Loans. Conversely, Hong Kong bucked the trend and was led higher by consumer and EV stocks.
NOTABLE ASIA-PAC HEADLINES
- China's stats bureau said China will focus on implementing various policies and will further unlock the potential of domestic demand, while it noted global conditions remain uncertain and volatile. Furthermore, it stated that China's domestic supply-demand imbalance remains pronounced and China's economic growth momentum needs to be strengthened, as well as vowed that China will improve supply, advance reforms and expand opening-up.
- Japanese Economy Minister Kiuchi said they expect improvement in employment and income environment to underpin a gradual economic recovery, adding that they need to continue closely monitoring the impact from the Middle East situation. Following the Q3 GDP figure, Kiuchi said private consumption was impacted by higher prices from Middle East tensions, natural disasters and bad weather.
NOTABLE APAC DATA RECAP
- Chinese Industrial Production (Oct YY) 4.8% vs. Exp. 5.3% (Prev. 5.5%).
- Chinese Retail Sales (Oct YY) 0.4% vs. Exp. 0.8% (Prev. 1.1%).
- Chinese Fixed Asset Investment (YTD) (Oct YY) -8.1% vs. Exp. -7% (Prev. -7.2%).
- Chinese Unemployment Rate (Oct) 5.1% vs. Exp. 5.2% (Prev. 5.2%).
- Chinese House Price Index (Oct YY) -2.4% (Prev. -2.8%).
- Japanese GDP Growth Rate Prel (Q3 QQ) 0.0% vs. Exp. 0.1% (Prev. 0.4%).
- Japanese GDP Growth Annualised Prel (Q3) -0.1% vs. Exp. 0.3% (Prev. 1.4%).
- Japanese Industrial Production Final (Sep YY) 1.7% vs. Exp. 1.9% (Prev. 2.7%).
- Japanese Industrial Production Final (Sep MM) 2.0% vs. Exp. 2.2% (Prev. -2.4%).