
Published:
Newsquawk Desk
US Market Open: Trump reiterated that the war with Iran will end soon; JPY gains following a BoJ source report, whilst the DXY is pressured alongside yields and oil prices
0:00--:--
- US President Trump said the war with Iran will end very soon and that oil prices will fall once the conflict concludes, while Saudi Arabia conducted further strikes against Houthi targets in Yemen.
- The BoJ is reportedly leaning back against back-to-back hikes in October but could hawkishly adjust inflation language, according to Bloomberg.
- US equity futures mixed, with the NQ underperforming as chip names continue to slip.
- DXY pushed lower by higher yields; JPY outperforms following BoJ sources.
- Fixed income benchmarks gain on a flight to safety and lower energy prices (Brent -1.7%).
- Looking ahead, highlights include US ADP Employment Change Weekly, Existing Home Sales (Sep), OPEC MOMR. Speakers include ECB's Lane, Fed’s Barkin & Collins. Earnings from UnitedHealth, JPMorgan, Goldman Sachs, Wells Fargo, Citi, Johnson & Johnson.
SNAPSHOT
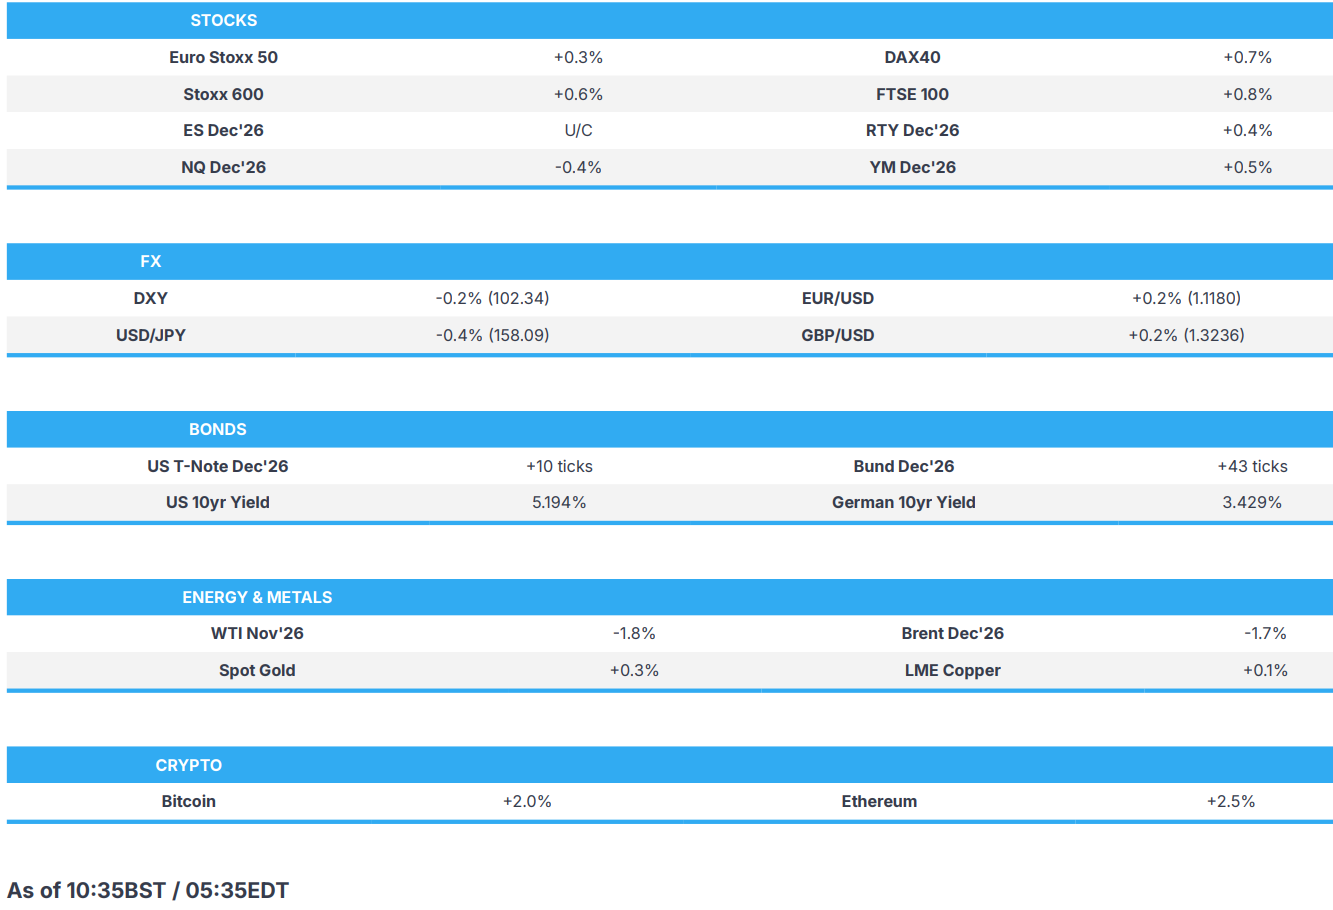
EUROPEAN TRADE
EQUITIES
- European bourses (STOXX 600 +0.6%) have moved higher throughout the session. There was earlier underperformance in the tech–heavy AEX (+0.1%), but it has since climbed into the green. Initial pressure stemmed from the slump in tech behemoths in Asia and throughout the US trading session on Monday. The drivers seem to be two-fold: 1) increased competition after CXMT said they made progress on new memory architecture, as they plan to roll out a new server-memory product by year-end, according to SCMP, 2) Broadcom CEO likens market sentiment to a casino and highlights concerns about AI buildout financing. Tech continues to be in favour for fund managers, with a BofA survey showing that the proportion of managers overweight tech has risen to 37% (prev. 30%).
- Sectors highlight the positive bias. Chemicals top the sector pile, with Health Care and Real Estate following closely behind. The sector laggards include Tech, Consumer Products & Services and Basic Resources.
- LVMH (-1.5%) reported Q3 sales after the close on Monday. Headline revenue beat estimates; however, the widely watched Fashion & Leather Goods fell 5% (exp. -1.57%). As expected, struggles in China were highlighted as a major challenge, while the CFO added that short-term cost-cutting will not increase sales.
- US equity futures are mixed, with underperformance in the NQ. Outside of the tech story, focus will be on banking earnings, with JPM, GS and C set to report.
- Click for the sessions European pre-market equity newsflow
- Click for the additional news
FX
- Snapshot: DXY is under pressure this morning, owing to easing yields and a pullback in energy benchmarks. The downside in oil does not have a specific catalyst, and it appears to be more of a pullback from yesterday’s advances. Overall, the geopolitical situation remains tense with Saudi striking Houthi targets overnight; elsewhere, a merchant ship was sunk off Bulgaria’s Black Sea coast. Given the USD pressure, G10s are stronger, albeit to varying degrees; the JPY outperforms, whilst the CAD posts only mild gains.
- DXY holds within a 102.30 to 102.57 range. As mentioned, pressure comes alongside easing yields/energy, with domestic newsflow focused on the Fed’s Waller. He mentioned that recent high yields are somewhat attributed to the AI buildout. Interestingly, he noted that recent yield levels are doing some of the Fed’s work on demand. No reaction was seen on the comments, but remarks are not too dissimilar from those seen in the ECB Minutes.
- JPY outperforms vs peers, following reports in Bloomberg, citing sources, which suggested that the BoJ is leaning back against back-to-back hikes in October. Instead, the Bank may change the language surrounding its 2% target to signal that it is “approximately” at the level, rather than “approaching” it. This essentially corroborates a Reuters source report from earlier in the month, but still managed to spur a hawkish reaction in the JPY. MUFG (following the Reuters piece) suggested that the language change will back its case for a December hike.
FIXED INCOME
- The bullish APAC performance remains, but has not extended, in the European morning thus far. Despite a number of potential catalysts occurring, nothing has fundamentally shifted the dial from a FTQ on the tech sell-off and energy downside, as the Middle East backdrop has not escalated.
- USTs firmer by around 10 ticks as things stand, but only a tick or two above the APAC peak. No move at the time to Fed’s Waller, but his comment that higher yields are doing some of their work is notable, though in-fitting with his dovish-bias. At the upper-end of 104-18 to 104-30+ parameters.
- Bunds followed suit overnight, and have extended by a few ticks to a 121.44 peak this morning, higher by 49 ticks at best. Specifics for the space light, no move to the unrevised German final inflation print and weak Bobl auction. Regional focus remains on familiar factors for the bloc and Germany specifically.
- Gilts gapped higher by just over 10 ticks, before climbing to an 84.47 peak in short order, and since then have held just off that but still with gains in excess of 50 ticks. Aside from the above points and the usual, relatively speaking, larger move seen on energy action, Gilts react to a few factors today. A UK court ruling which significantly increases the odds of the Treasury keeping c. GBP 4bln in seized crypto holdings; a windfall for Chancellor Healey. Additionally, a FT source report suggests that CGT will not be equalised to Income Tax, though it could still see an increase; a reported view taken by the, unsurprising, view that such an increase would increase capital outflows from the UK.
- Italy sells EUR 7bln vs Exp. EUR 5.5-7bln 3.00% 2029, 3.35% 2033 and 3.95% 2041 BTP.
- The UK sells GBP 500mln 4.00% 2063 Gilt via Tender: b/c 3.98x (prev. 3.51x), average yield 5.802% (prev. 5.722%).
- Australia sells AUD 300mln 3.00% March 2047 bonds: b/c 3.60x, avg. yield 5.6818%.
COMMODITIES
- WTI Nov and Brent Dec futures are softer, extending their pullback from yesterday's gains as Trump reiterated that the Iran war will end very soon, while talks between Washington and Tehran continue through intermediaries. Nonetheless, diplomatic progress remains limited, with reports this morning suggesting the two sides remain divided over the sequencing of an agreement, although Iranian FM Araghchi reiterated that Tehran is seriously pursuing diplomatic efforts. Meanwhile, Iran continues to insist on its conditions for reopening Hormuz, while Houthi attacks on Saudi Arabia and the US Gulf production shut-ins remain supportive for the complex. WTI has fallen to a USD 91.81/bbl low from a USD 93.49/bbl peak, while Brent has declined to USD 104.71/bbl from USD 106.14/bbl highs.
- Dutch TTF is firmer amid upcoming colder weather in the Western Hemisphere alongside continued Middle Eastern supply concerns. TTF has climbed from a EUR 83.90/MWh low to EUR 86.40/MWh highs.
- Precious metals are firmer, with spot gold benefiting from lower global yields and a softer DXY amid softer oil prices, although expectations of further Fed tightening keep upside capped. Spot gold has risen from a USD 4,151/oz low to USD 4,201/oz while spot silver has gained within a USD 59.58-60.73/oz range.
- Base metals are mixed, with copper flat amid the broader risk-off tone across the tech sector. 3M LME copper has risen within a USD 14,549.68-14,667.00/t range, while COMEX copper is firmer within a USD 6.7030-6.7725/lb range.
- Maersk (MAERSKB DC) and Hapag-Lloyd (HLAG GY) will re-launch the FM1 service on the route between Asia and the Middle East.
- Kuwait lowered November crude prices for November, according to the pricing document.
TRADE/TARIFFS
- Western auto executives warned the EU’s deal with Beijing to restrict hybrid vehicle imports into the bloc will offer only “temporary” protection, as Chinese rivals push ahead with their ambitions to expand sales across the continent, according to FT.
- China proposes civil aviation dual-use export rules to facilitate compliant exports for aviation enterprises.
NOTABLE EUROPEAN HEADLINES
- UK Chancellor Healey is reportedly rejecting calls to equalise capital gains tax and income tax rates, the FT reported citing sources. The report added that the Treasury could still decide to raise CGT by a small amount and also said the Treasury is working on CGT relief to encourage entrepreneurs who sell their business to reinvest back in the UK.
- Retail bosses are to warn UK Chancellor Healey that a tax raid on shops will push up prices and worsen the cost of living crisis, according to Telegraph.
- UK grocery price inflation accelerates to 2.5% in the four weeks to October 4th (vs 2.3% in the 4 weeks to Sep), according to Worldpanel.
- German Chancellor Merz said Germany needs to increase its long-term growth potential. Merz added that he wants a comprehensive pension reform and that there will be temporarily higher contributions paid by workers and employers into the pension system.
NOTABLE EUROPEAN DATA RECAP
- German HICP Final (Sep YY) 3.3% vs. Exp. 3.3% (Prev. 2.9%).
- German HICP Final (Sep MM) 0.6% vs. Exp. 0.6% (Prev. 0.2%).
- UK BRC Retail Sales Monitor (Sep YY) 1.0% vs. Exp. 0.7% (Prev. 0.5%).
- UK Barclays Consumer Spending YY (Sep) 2.0% (prev. 2.1%).
CENTRAL BANKS
- Fed's Waller (Voter, Dovish) said the US remains the dominant country in building AI models and that AI could contribute to widening GDP per capita. If AI investment falls off, it will put a check on prices and that hyperscalers are still planning on spending trillions of dollars over the next three years. On the bond market and yields, Waller said the AI build-out is definitely having an impact on yields and that real yields reflect the impact of real growth. Waller went on to say that higher yields could do some of the Fed's work on demand and that inflation expectations are well anchored.
- Fed's Hammack (2026 voter) reiterated that more restriction is needed, but she is keeping an open mind on pace of rate hikes and noted that policy restriction will need to hit demand, either through capital spending or consumption. Furthermore, she said inflation pressures are broadening out from AI, with other firms all doing well and ready to invest, while she doesn't want to discourage growth but stated that they may need to 'pull it back a little bit'.
- The BoJ is reportedly to lean back against back-to-back hikes in October, Bloomberg reported citing sources. The source added that the BoJ could adjust language on the 2% inflation target from "approaching 2%", to "approximately 2%", while also suggesting that December is still in play.
- BoJ Governor Ueda reiterated the BoJ's stance that market determines long-term interest rates and will continue to closely monitor bond markets, adding that long-term interest rates are determined in the markets and reflecting various factors. Ueda said core inflation is gradually nearing 2% and that it is important to anchor inflation around 2% now.
- RBA Minutes from the September Meeting stated the Board was concerned excess demand in the economy was greater than previously assumed and it saw an increased risk of persistently elevated inflation, while it reiterated it will increase rates further if needed. All board members had agreed that a 25bps rate hike was necessary, and the Board briefly weighed the case for keeping rates unchanged, including a decline in house prices. Furthermore, it discussed upside inflation risks and factors that could sustain higher inflation, as well as noted that some upside inflation risks had already emerged or intensified since August, and the Board highlighted the need to adjust rates in a timely manner to keep inflation expectations anchored.
- BoE's Greene (hawkish dissenter) said a bigger risk is not being proactive enough in tackling inflation than raising rates too soon, while she warned if they wait until second-round effects materialise, it will be too late. Greene noted concern about successive supply shocks and stated they must be proactive in leaning against second-round effects, as well as stated that UK monetary policy is not that restrictive.
- ECB's Elderson said the heatwave in Europe may have imposed costs equivalent to the area's projected 2026 economic output, underscoring a potentially material macroeconomic risk.
NOTABLE US HEADLINES
- IMF raised 2026 Global Real GDP growth forecast to 3.1% (prev. 3.0%), citing AI investment tempering energy price shock in key economies, while it maintains 2027 global growth view at 3.4%. Maintained US 2026 growth forecast at 2.3% and raises 2027 forecast to 2.3% (prev. 2.2%), lowered China 2026 GDP forecast to 4.5% (prev. 4.6%) and cut 2027 forecast to 4.0% (prev. 4.1%), raised Euro Area 2026 GDP forecast to 1.1% (prev. 0.9%).
GEOPOLITICS
MIDDLE EAST
- US President Trump said the Houthis are misbehaving very badly and that he spoke with Saudi Crown Prince MBS about attacks, while he also stated that oil will drop when the war with Iran ends very soon and that the Midterm elections will have no impact on his decisions regarding Iran.
- US President Trump said Iran will never get nuclear weapons and that this war will end very soon, with gas prices to go down as soon as the war ends, while Trump said he had to change the course a little bit on Iran because they couldn't let Iran get a nuclear weapon.
- US President Trump posted, "I see so many comments from the Radical Left Morons and Lunatics that China and Russia are helping the “wonderful” Islamic Republic of Iran. If they are, it’s at a very low level, but I don’t believe they are at all. They have too much to lose, and we would know about it, and know about it very fast!"
- Iran's Foreign Minister Araghchi said that the Foreign Ministry is seriously pursuing the use of diplomatic capabilities to secure national interests, IRIB reported.
- IRGC commander-in-chief said no extra-regional power has the right to threaten and maintain a hegemonic presence or interfere in the Strait of Hormuz and the Persian Gulf.
- Iran and the US remain divided over the sequencing of a diplomatic agreement, Al-Akhbar reported citing sources. The source said that Tehran is demanding an end to the war, removal of the naval blockade and oil sanctions, and release of frozen assets before reopening the Strait of Hormuz and discussing nuclear issues while Washington is insisting on nuclear concessions first.
- Iran is fortifying defences, rallying loyalists and threatening a wider, harsher response against the US and its Gulf allies as it prepares for a potential resumption of attacks after the Midterms and seeks to deter them, according to WSJ.
- Yemen's Houthis said they targeted Riyadh Airport with ballistic missiles on Monday, while the group also carried out an operation targeting Khamis Mushait Air Base with a drone. Furthermore, it was reported that air traffic at King Fahd International Airport in Dammam was temporarily halted.
RUSSIA-UKRAINE
- US President Trump said Ukrainian President Zelensky and Russian President Putin have to get together and end the war, while he added that they both don't know how to make a deal, but he thinks they support the energy ceasefire. Furthermore, Trump said he thinks Putin wants to make a deal more than Zelensky, and that Zelensky has to focus on making a deal, not talk.
OTHER
- North Korea confirmed it test-fired a tactical ballistic missile, while North Korean leader Kim said North Korean weaponry will be developed and completed more strenuously, according to KCNA.
- US President Trump said he may meet with North Korean leader Kim and it would be exciting, while he also said that he is considering firing the US ambassador to Greece.
- Belize's Foreign Ministry rejected China's sanctions and said measures against Belize's Foreign Minister are unwarranted.
CRYPTO
- Bitcoin rebounds from Monday's losses and has regained the USD 83k handle after falling to a trough of USD 80.93k.
APAC TRADE
- APAC stocks mostly declined amid a tech sell-off following the mixed handover from Wall Street, where the Nasdaq underperformed as chip and memory names were pressured by China competition concerns after CXMT announced technological progress on a denser memory chip design.
- ASX 200 outperformed its regional peers with price action range-bound as the downside in tech and miners was offset by strength in energy, financials and defensive sectors.
- Nikkei 225 suffered from the tech-related pressure as participants returned from the long weekend.
- KOSPI slumped alongside the tech sell-off, with a sidecar triggered early on due to heavy losses.
- Hang Seng and Shanghai Comp conformed to the tech-led declines across the region, with weakness in autonames after reports that China will cut the VAT export tax rebate rate on new energy vehicles to 9% from 13%.
NOTABLE ASIA-PAC HEADLINES
- China smartphone shipments fell 15.4% in Q3, according to IDC.
- India's PM Modi said today's technology and data and knowledge and innovation are powers, adding that tech should help new opportunities for millions.
NOTABLE APAC DATA RECAP
- Japanese PPI (Sep YY) 6.8% vs. Exp. 7.6% (Prev. 7.6%).
- Japanese PPI (Sep MM) -0.3% vs. Exp. 0.5% (Prev. -0.2%).
- Australian NAB Business Confidence (Sep) -13 (Prev. -8).
Newsquawk Daily
Get both market opens in your inbox.
Free. No signup, no card.
Use the Platform