
US Market Open: NQ futures supported by upbeat SK Hynix earnings; Crude choppy following conflicting US-Iran updates
Newsquawk Analysts ·
Listen
0:00--:--
- NQ futures outperform following SK Hynix's upbeat earnings.
- DXY flat; NZD hit after the RBNZ unexpectedly held rates steady.
- Fixed income benchmarks modestly lower ahead of the UK Budget and Fed rate decision.
- Crude complex choppy, with conflicting reports regarding a new proposal to end US-Iran conflict.
- Looking ahead, highlights include US Atlanta Fed GDPNow, Fed Policy Announcement (Oct), BoC Policy Announcement (Oct), UK Autumn Budget. Speakers include BoC’s Macklem & Fed Chair Warsh. Supply from Germany & the US. Earnings from Phillips 66, Microsoft, Alphabet, ServiceNow, FedEx, T-Mobile, Ford & Airbus.
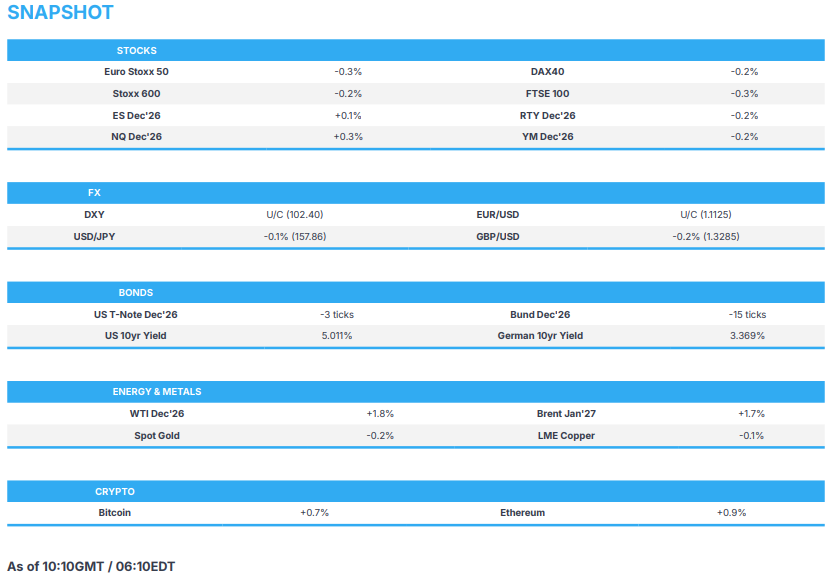
EUROPEAN TRADE
EQUITIES
- European bourses (STOXX 600 -0.2%) are lower across the board, with underperformance in Spain’s IBEX (-1.4%) as the heavy weighting of Santander hits the index. Little upside was seen following a geopolitical report from Reuters, which stated that Qatari mediators presented Iran with a new draft deal in Tehran on Sunday, with Iran considering the proposal and a response expected by the end of the week. However, this report was pushed back from a senior Iranian official, saying that Qatar has not presented a new proposal to end hostilities.
- A busy morning for European banking names. Starting in Switzerland, UBS (-2.0%) reported mixed results. Revenue and client inflows into the wealth unit beat estimates while net income and IB pretax income missed. The Swiss bank also declined to say whether it would expand its USD 3bln share buyback programme. BNP Paribas (-0.2%) had a more positive report, with a strong beat in its equity trading revenue, and announced a EUR 1.3bln share buyback for next month. Over in Spain, Santander’s (-3.5%) results came in broadly in line with estimates, and the bank said it is comfortably on track to meet 2026 targets. Germany’s Deutsche Bank (+3.2%) posted FIC Sales & Trading revenue that fell 3% in the period but outperformed its US peers, which is seemingly supporting shares this morning. Net income and pretax profit also beat consensus. To wrap up the banking earnings, Standard Chartered (+3.3%) reported pretax profit that beat estimates, raised its operating income growth forecast above a previous range of 5% to 7%, and now expects RoTE to reach about 14% in 2026, up from more than 12%.
- Other key earnings include: Mercedes-Benz +0.6%, revenue misses while adj. EBIT beat but points to continued growth in Europe and the US, as well as record EV sales; BASF -0.8%, despite lifting its 2026 EBITDA before special items guidance; Equinor -0.4%, despite adj. operating income beating estimates and raising its 2026 production growth guidance; Heineken +0.9%, total volume tops expectations and reiterates its guidance.
- US equity futures are mixed, with outperformance in the NQ given the upbeat SK Hynix earnings. Another busy earnings slate today, but focus will be after-hours when Alphabet and Microsoft report.
- SK Hynix (000660 KS) - Q3 2026 (KRW): Net Income 39.5tln (exp. 55.4tln), Operating Profit 83.3tln (exp. 76.7tln), Revenue 104.6tln (exp. 98.3tln). Announces shareholder return of c. KRW 100tln in 2026, with cash dividend of more than KRW 30tln and decides on a KRW 20tln share buyback. Shares rose 10.9% in Asia trade.
- Click for the session's European pre-market equity newsflow
- Click for the additional news
FX
- DXY is relatively flat this morning in a narrow 102.31-102.49 range (vs yesterday’s 101.99-102.40 range) ahead of the FOMC policy announcement (at 18:00 GMT) and press conference later today. The Fed is widely expected to hold rates at 3.75-4.00% in October despite hotter-than-expected inflation, as softer jobs data and dovish-leaning commentary from key officials support a pause, although a 25bps hike is widely anticipated in December and some policymakers may dissent in favour of immediate tightening (full Newsquawk preview available in the Research Suite). Analysts at ING also suggest that the key threat in recent weeks has been the AI woes, although earnings from large names in the space are watering down those fears, with SK Hynix reporting strong numbers overnight.
- GBP slightly subdued, as it looks ahead to the UK Autumn Budget. On the latter, the Budget is expected to be relatively uneventful, with Chancellor Healey likely to maintain fiscal headroom of around GBP 15bln (prev. GBP 23.6bln), potentially raise the bank surcharge and announce additional energy and defence spending, while higher Gilt issuance and persistent fiscal concerns pose downside risks to UK assets, although a further reduction in long-end issuance could cushion the market reaction (full Newsquawk Primer available). GBP/USD trades in a 1.3272-1.3312 range with the next downside level being the Friday 16th low at 1.3262.
- For the EUR, Dutch TTF prices remain near EUR 100/MWh as the ECB tomorrow is widely expected to hold rates at 2.50% and maintain its data-dependent, meeting-by-meeting approach, as French fiscal and political uncertainty alongside tighter financial conditions support a pause, despite elevated energy prices and hotter-than-expected inflation, with markets still pricing further tightening by year-end. EUR/USD resides in a narrow 1.1113-1.1132 range after finding some support not far from its 200 WMA (1.1106).
- NZD slumped overnight as the RBNZ unexpectedly held the Official Cash Rate at 2.75% (exp. 25bps hike to 3.00%) via a 4-3 split decision citing global uncertainty, although Governor Breman reiterated that tighter policy will likely be required depending on the economy.
- AUD outperforms after Australian inflation accelerated more than expected in September, with CPI up 1.3% Q/Q (exp. 1.3%; prev. 0.6%) and 4.3% Y/Y in September (exp. 4.2%; prev. 4.0%), while the RBA’s trimmed mean gauge rose 3.7% Y/Y (exp. 3.6%; prev. 3.6%), raising expectations of a fifth rate hike at its 3rd November meeting.
- CAD looks ahead to the BoC announcement later today (at 13:45 GMT), where the central bank is expected to hike rates by 25bps, with money markets pricing an 84% chance of an increase, as elevated energy prices, rising inflation expectations and hawkish commentary from Governor Macklem support tightening, despite weakening employment and headline CPI undershooting forecasts.
FIXED INCOME
- Another relatively contained morning for USTs. Some two-way action on geopolitical updates, which resulted in the 105-26 to 106-03 confines USTs currently reside in, but the benchmark is near enough flat in that as it stands.
- The US day is dominated by the Fed, though with over a 90% implied probability of an unchanged outcome the risks are skewed to an uneventful announcement. Thereafter, scrutiny will be on the vote split, while Chair Warsh is unlikely to give too much away given his known disdain for forward guidance.
- Bunds are lower by around 15 ticks, but around 10 clear of a 121.76 base. Specifics for the bloc are light. Action has been a function of energy moves across the morning as crude and Dutch TTF tick higher once again, while we count down to Thursday’s ECB.
- Gilts are in line with EGBs into the UK Budget. They are holding just off an 84.72 WTD base. For the Budget, the expectation is a relatively uneventful affair; however, the risks are to pressure in Gilts and upside in yields from the speech and OBR forecasts, while the DMO remit could then serve to offset this, if there is as expected a further skew away from the long end.
COMMODITIES
- WTI Dec’26 and Brent Jan’27 are firmer, with the former in a USD 99.75-102.24/bbl range (vs yesterday’s USD 99.44-102.82/bbl range) and the latter in a current USD 109.62-111.77/bbl range (vs yesterday’s USD 109.02-111.91/bbl range). Downticks this morning were seen after Reuters sources reported that Qatari mediators presented Iran with a new draft deal on Sunday, with Tehran expected to respond by the end of the week; the proposal includes a seven-day timeline for daily confidence-building measures by both sides, potentially beginning early next week, with several countries acting as guarantors. However, more recently, this was pushed back from a senior Iranian official, reportedly saying that Qatar has not presented a new proposal to end hostilities. Further, overnight it was reported that the US told several Gulf Arab countries to be prepared for a short, intense military campaign after the US midterm elections, according to WSJ sources. Elsewhere, uncertainty remains in Israel following an inconclusive vote, as Israeli PM Netanyahu’s bloc and the opposition camp both failed to secure a majority (largely as expected). Final results are expected in the coming days.
- Dutch TTF is on a firmer footing and meanders in a current intraday range between EUR 96.75/MWh and 98.25/MWh at the time of writing, as Western storage woes continue to bite ahead of winter and with QatarEnergy yesterday declaring an LNG force majeure on Edison and some South Asian clients till December. Elsewhere, US Energy Secretary Wright said the suspension of sanctions on Russia was temporary and that the US was ramping up LNG exports, while he added that Russia could not currently export diesel and that flows of refined products through the Strait of Hormuz had increased. Wright also commented that the Iran war has come at a cost and that the war with Iran is unfortunate timing.
- Metals are lower across the board despite a relatively stable USD, but amid the rebound in energy prices ahead of the FOMC. Spot gold is subdued in a USD 4,028-4,070/oz range (vs yesterday’s USD 3,989-4,066/oz range). Spot silver is lower and resides in a USD 53.69-54.53/oz range (vs yesterday’s USD 52.66-54.55/oz range). 3M LME copper trades in a USD 14,448.43-14,503.00/t range at the time of writing.
- US Weekly Private Energy Inventory Data (bbls): Crude -2.0mln (exp. +0.5mln), Gasoline +2.4mln (exp. -1.3mln), Distillate +0.4mln (exp. -0.9mln), Cushing -0.5mln.
- US President Trump said he is terminating Biden's methane regulations.
TRADE/TARIFFS
- Canadian official said limited progress was made in US trade talks, while it was separately reported that Canada and the UAE signed an economic partnership agreement.
NOTABLE EUROPEAN HEADLINES
- UK confirmed it will be removing the standing charge on gas bills and Ofgem will be directed to do this in 2027, or as soon as possible.
- UK Chancellor Healey prepares to slash household gas bills by GBP 50, according to Telegraph.
- UK Chancellor Healey is to reverse cuts to cash ISA allowances, and he will use the Budget to maintain the tax-free limit at GBP 20,000 a year, reversing a plan by his predecessor, according to FT.
- UK Chancellor Healey is set to fund the Defence Investment Plan in full during the Budget, The Sun's Elsom reported citing sources.
NOTABLE EUROPEAN DATA RECAP
- German GfK Consumer Confidence (Nov) -30.8 vs. Exp. -30.9 (Prev. -30.6).
- Italian Industrial Sales (Aug MM) -0.90% (Prev. 1.70%).
CENTRAL BANKS
- RBNZ kept the OCR unchanged at 2.75% (exp. 25bps hike) with the decision made by a 4-3 vote split (Breman, Hansen, Gai and Williams voted for a hold, while Conway, Gourley and Silk voted for a hike). RBNZ said members agreed on the inflation outlook but differed in their assessment of risks and the timing of the monetary policy response, while the committee agreed that tighter monetary policy is likely to be required, but remains dependent on the economic outlook. RBNZ also stated there is a risk that inflation becomes entrenched before conventional inflation expectations measures respond, despite the previous two OCR hikes, and the committee remains focused on the medium-term inflation outlook.
- RBNZ Governor Breman said during the post-meeting press conference that they agreed tighter policy will likely be required, conditional on the economy, while she added that the committee discussed a decline in NZD, which if sustained could add to imported inflation. Breman also stated that further tightening might be needed, even into restrictive territory and that they are likely to implement further rate increases at upcoming meetings. Furthermore, they discussed whether the OCR path will need to be lifted, and she commented that it is likely the OCR is to rise higher than the previous path.
- RBA Governor Bullock said a key question is whether monetary policy tightening so far will be sufficient to return inflation to target within a reasonable timeframe, while she added they remain committed to the mandate of delivering price stability and full employment. Bullock said she recognises that higher interest rates can be challenging, but cannot allow elevated inflation to persist, and that oil and related prices have risen sharply again and will contribute materially to inflation, with inflation likely to exceed the August base-case forecast. Furthermore, she said upside inflation risks are materialising and that inflation is far too high.
NOTABLE US HEADLINES
- US Senator Warren (D) reportedly raised concerns over risks disclosed in Anthropic's IPO filings and is demanding answers to a series of questions ahead of its planned listing, WSJ reported citing sources.
- US Transportation Secretary Duffy is to announce approval of a licence application for a USD 8.2bln deepwater LNG export port at Port Houston during a visit to Texas on Wednesday, Punchbowl reported.
- South Korea fined Google (GOOGL) and Apple (AAPL) KRW 63.7bln for requiring in-app payments.
GEOPOLITICS
MIDDLE EAST
- Qatari mediators reportedly presented Iran with a new draft agreement on Sunday aimed at ending the conflict with the US and Israel, with Tehran expected to respond by the end of the week. The proposal outlines a seven-day timeline of daily confidence-building measures addressing both sides' concerns, potentially beginning early next week, with several countries acting as guarantors, according to Reuters citing an official briefed on the negotiations.
- However, according to Reuters citing a senior Iranian official, Qatar has not presented a new proposal to end hostilities between Iran and the US and that Tehran's policy of showing no flexibility over the nuclear issue remains unchanged.
- US President Trump replied anything is possible when asked if there will be strikes against Iran after the election.
- US told several Gulf Arab countries to be prepared for a short, intense military campaign after the US midterm elections, according to people briefed on the conversations cited by WSJ.
- Iranian Foreign Minister Araghchi said sustainable regional security requires collective responsibility, mutual respect for sovereignty and cooperation among regional countries without foreign military intervention. In later comments, Araghchi said the destructive consequences of any military adventurism provoked by Israel in the Persian Gulf region for international markets remain a serious concern for gas exporting and gas consuming countries.
- Iranian source denied a report of a Trump-backed plan being delivered via Pakistan's army chief, stating this was completely false and that no new proposal was presented to Iran. The source added that Tehran's conditions are clear, and without a convincing response and tangible implementation, the Strait of Hormuz won't reopen.
- Israeli PM Netanyahu and rival Eisenkot both claim a mandate to lead the country following Tuesday's inconclusive election. With 48.4% of votes counted, Netanyahu's bloc is projected to secure 55 seats, Eisenkot's bloc 50 seats and Arab parties 15 seats, according to Israeli media. Seat projections remain subject to change, with definitive results expected by Thursday.
RUSSIA-UKRAINE
- US President Trump said there will be a meeting with Russian President Putin and Ukrainian President Zelensky set up soon, while Trump also stated there will be a meeting on disarmament during his Asia trip.
- Russian Deputy Foreign Minister Ryabkov said Russia remains in the preparatory phase for negotiations on Ukraine, TASS reported.
- Ukrainian President Zelensky said Ukraine will not attack Russian ships carrying diesel for the US. Furthermore, he said that Western powers could eventually discuss Russia's demands for security guarantees, but insists Ukraine's own security needs must be addressed first.
CRYPTO
- Bitcoin currently trades at the upper end of its USD 80.49k-81.69k range, as it continues to rebound from last week's trough of USD 79.11k.
APAC TRADE
- APAC stocks were mostly higher as the region followed suit to the gains on Wall Street, where the Nasdaq outperformed as tech stocks continued to shrug off recent AI-related concerns, while participants digested SK Hynix earnings and awaited the looming risk events, including central bank decisions.
- ASX 200 pared initial gains and returned to flat territory as hotter inflation data and hawkish RBA rhetoric boosted rate hike bets for next week's RBA meeting.
- Nikkei 225 briefly climbed back above the 64,000 level, with the index led higher by tech strength.
- KOSPI outperformed on the tech momentum, which was also facilitated by SK Hynix shares rallying after its operating profit rose 632% Y/Y to a record KRW 83.3tln, while revenue rose 328% Y/Y to surpass KRW 100tln for the first time, and it also plans to return about KRW 100tln to shareholders this year.
- Hang Seng and Shanghai Comp conformed to the positive mood after the PBoC continued with its firm liquidity efforts, although the upside was capped amid a slew of earnings results and with Pop Mart flagging as much as a 50% drop in Q3 revenue.
NOTABLE ASIA-PAC HEADLINES
China rushes to shore up struggling markets with the ‘National team’ of funds and brokers buying stocks as investors turn away from AI trade, according to FT.
Taiwan Central Bank Governor affirmed that Taiwan has the capacity to establish a sovereign wealth fund and said the relative weakness of the TWD this year is due to foreign investors taking profits on Taiwan stocks.
NOTABLE APAC DATA RECAP
- Australian CPI (Sep YY) 4.3% vs. Exp. 4.2% (Prev. 4.0%).
- Australian CPI (Sep MM) 0.8% vs. Exp. 0.7% (Prev. 0.4%).
- Australian RBA Trimmed Mean CPI (Sep YY) 3.7% vs. Exp. 3.6% (Prev. 3.6%).
- Australian RBA Trimmed Mean CPI (Sep MM) 0.3% vs. Exp. 0.3% (Prev. 0.2%).
- Chinese outstanding individual mortgage loans (Sep) -4.1% Y/Y; outstanding property loans -5.2% Y/Y.