
BoE Asset Purchase Facility Update (2026): 46bln (exp. GBP 50bln, prev. GBP 70bln); Horizon: --- (prev. 40/40/20)
The APF decision is the annual reset of the gilt unwind pace, and the market reads it through the supply channel rather than the policy channel: the MPC has consistently treated the unwind as a background operation, leaving Bank Rate to carry the tightening burden.
Novo Nordisk (NOVOB DC) denecimig demonstrates tolerability after switch from emicizumab in FRONTIER5 study of people with hemophilia A as published in the Journal of Thrombosis and Haemostasis
Coreweave (CRWV) announces proposed USD 3.0bln convertible senior notes offering
BoE Asset Purchase Facility Update (2026): 46bln (exp. GBP 50bln, prev. GBP 70bln); Horizon: --- (prev. 40/40/20)
STATEMENT: BoE holds rates at 3.75%, as expected; votes 6-3 (exp. 6-3), with Greene, Mann and Pill voting for a 25bps hike; APF gilt sales to be paused until April 2027
UK BoE MPC Vote Cut 0/ vs. Exp. 0/ (Prev. 0/)
Open the platform and use it. The whole workspace is free to try, with no signup and no card. When you want the headlines arriving live instead of on a delay, Newsquawk Pro is £24.99 for 7 days.
Votes:
- Votes 9-0 to unwind QT at an average annual pace of GBP 46bln through to 2034.
Auctions:
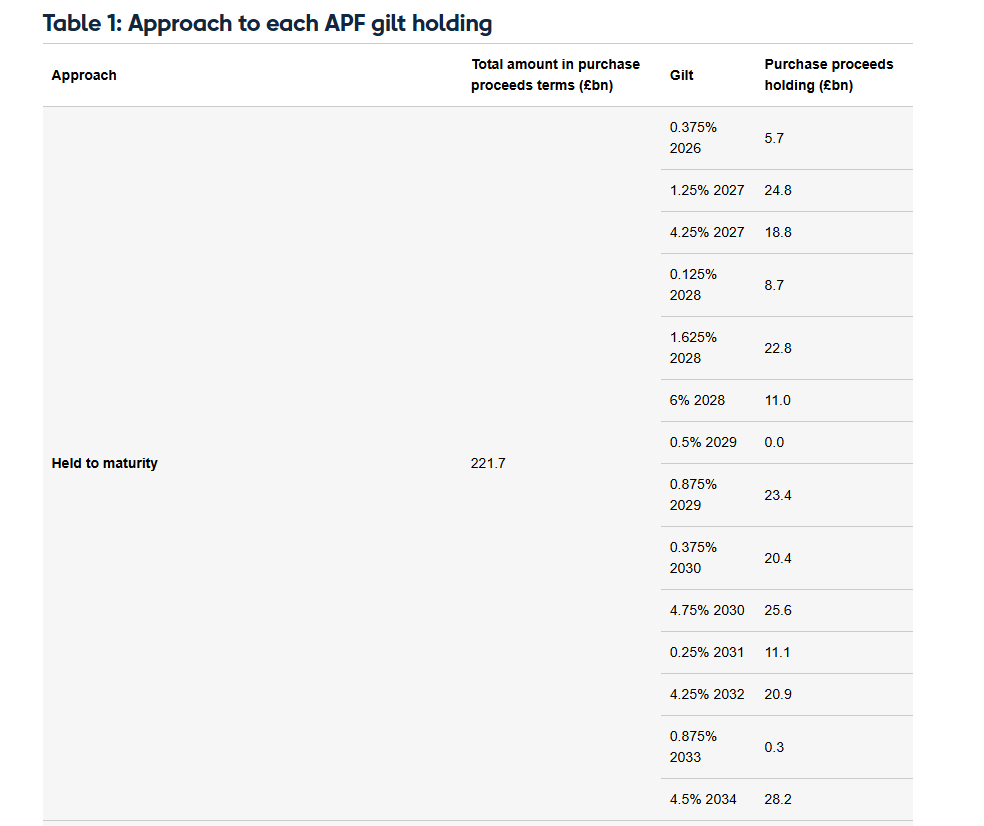
A slower pace than the prior GBP 70bln reduces the stock the Bank sheds through a given year, which matters because the reduction now runs through active auctions as well as passive runoff, and the shortfall against the roughly GBP 50bln consensus trims expected net issuance pressure once DMO financing needs are set against it. Previous resets of this kind have tended to land in the long end and in gilt-swap spreads rather than in front-end pricing, since the signal is about term supply, not the rate path; a unanimous 9-0 vote is in keeping with past APF decisions, which have rarely split the committee. The structure of the maturity buckets, previously tilted across short, medium and long tranches, is the detail that determines where in the curve the auction calendar bites, so the distribution matters as much as the headline total. The follow-ons are the DMO's remit revision, the revised auction schedule, and any comment on how active sales interact with periods of long-end volatility, which in past episodes has been the point where QT and gilt market functioning have collided.
Related headlines
- UK BoE Interest Rate Decision 3.75% vs. Exp. 3.75% (Prev. 3.75%)1 hour ago
- [PREVIEW] BoE Announcement on Thursday 17th September 2026 at 12:00 BST/07:00 EDT (REPOST)2 hours ago
- [MARKET ANALYSIS] European bourses helped by lower energy prices; RBI AV refutes Grizzly's short position3 hours ago
- [MARKET ANALYSIS] USD gives back some post-FOMC strength, whilst the GBP eyes BoE later today4 hours ago
- [PREVIEW] BoE Announcement on Thursday 17th September 2026 at 12:00 BST/07:00 EDT (REPOST)5 hours ago
- [MARKET ANALYSIS] Dollar takes a breather and holds on to post-FOMC spoils10 hours ago
- UK BoE MPC Vote Cut 0/ vs. Exp. 0/ (Prev. 0/)1 hour ago
- UK BoE MPC Vote Hike 3/ vs. Exp. 3/ (Prev. 3/)1 hour ago
- UK BoE MPC Vote Unchanged 6/ vs. Exp. 6/ (Prev. 6/)1 hour ago
- [ANALYSIS] Cheat Sheet: Bank of England September 17th announcement2 hours ago
- [ANALYSIS] Cheat Sheet: Bank of England September 17th announcement4 hours ago
- Raiffeisen Bank (RBI AV) pushes back on the Grizzly Research report, suggesting there are a number of misleading statements5 hours ago
- EUROPEAN OPEN: AAL LN-MMG Brazil deal deal faces EU competition concerns; AKZA NA-AXTA deal faces UK CMA probe; NXT beats in H1, raises FY26 guidance; GBF GY cuts FY26 outlook; NOVN SW ends ALS development after trial failure; Grizzly shorts RBI AV5 hours ago
- European Equity pre-Market Summary - 17th September 2026: European equity futures are indicative of a slightly firmer open; Bilfinger sinks after cutting guidance6 hours ago
- Newsquawk Daily European Equity Opening News - 17th September 20267 hours ago
- [MARKET ANALYSIS] Asia-Pac stocks trade mixed as partially weathers the hawkish FOMC meeting where the Fed hiked rates and the dotplots pencilled in another hike this year9 hours ago
- [MARKET ANALYSIS] Crude on a softer footing with newsflow relatively light on Thursday; metals firm despite FOMC losses4 hours ago
- European Movers: Anglo American (AAL LN) +1.1%, Bollore (BOL FP) -1.1%, Dassault Systemes (DSY FP) -2.4%, Raiffeisen Bank (RBI AV) -4.9%, Bilfinger (GBF GY) -24%5 hours ago
- [MARKET ANALYSIS] T-note futures are contained following post-FOMC selling10 hours ago
- PRE-MARKET TAIWAN AND SINGAPORE STOCKS NEWS: Taiwan Digital Minister Lin Yi-jing recently visited Washington, D.C., and met with US officials, think tanks and major technology companies to discuss cooperation on AI and cybersecurity11 hours ago
The whole workspace, free to try.
Try it free